
👋 Welcome back everyone,
The dividing line in autonomy used to run between camera and lidar, between Waymo’s caution and Tesla’s speed. This week it moved. The line now runs between operators who can prove their safety record with data and operators who ask for trust. Waymo lived on both sides of it within four days: one of the year’s biggest expansion announcements, its most embarrassing operational night since December, a federal warning letter, and then its answer, delivered as a peer-reviewed study rather than a press release. And Tesla picked the same week to go unsupervised in a third state.
⏱️ ~4700 words, 21 minute read

Ad
Autonomy is back in 2027. London, Munich, and Prague return next year, and speaker applications are now open.
If you’re working on something worth sharing with 250 senior mobility leaders, this is the forum for it. Previous speakers have included executives from Bolt, Pony AI, Apollo, Baidu, Wayve and Daimler. The format is intentionally intimate, with conversations that go beyond the usual conference presentations.
There are 200 speaking opportunities available across the series.
Four new cities, one bad night, and the new price of trust
Waymo’s four-city week
Let’s start with the expansion. Waymo activated fully driverless operations in Las Vegas this week, with Denver, San Diego, and Tampa next in line. Rides open to Alphabet employees first, then to the public.
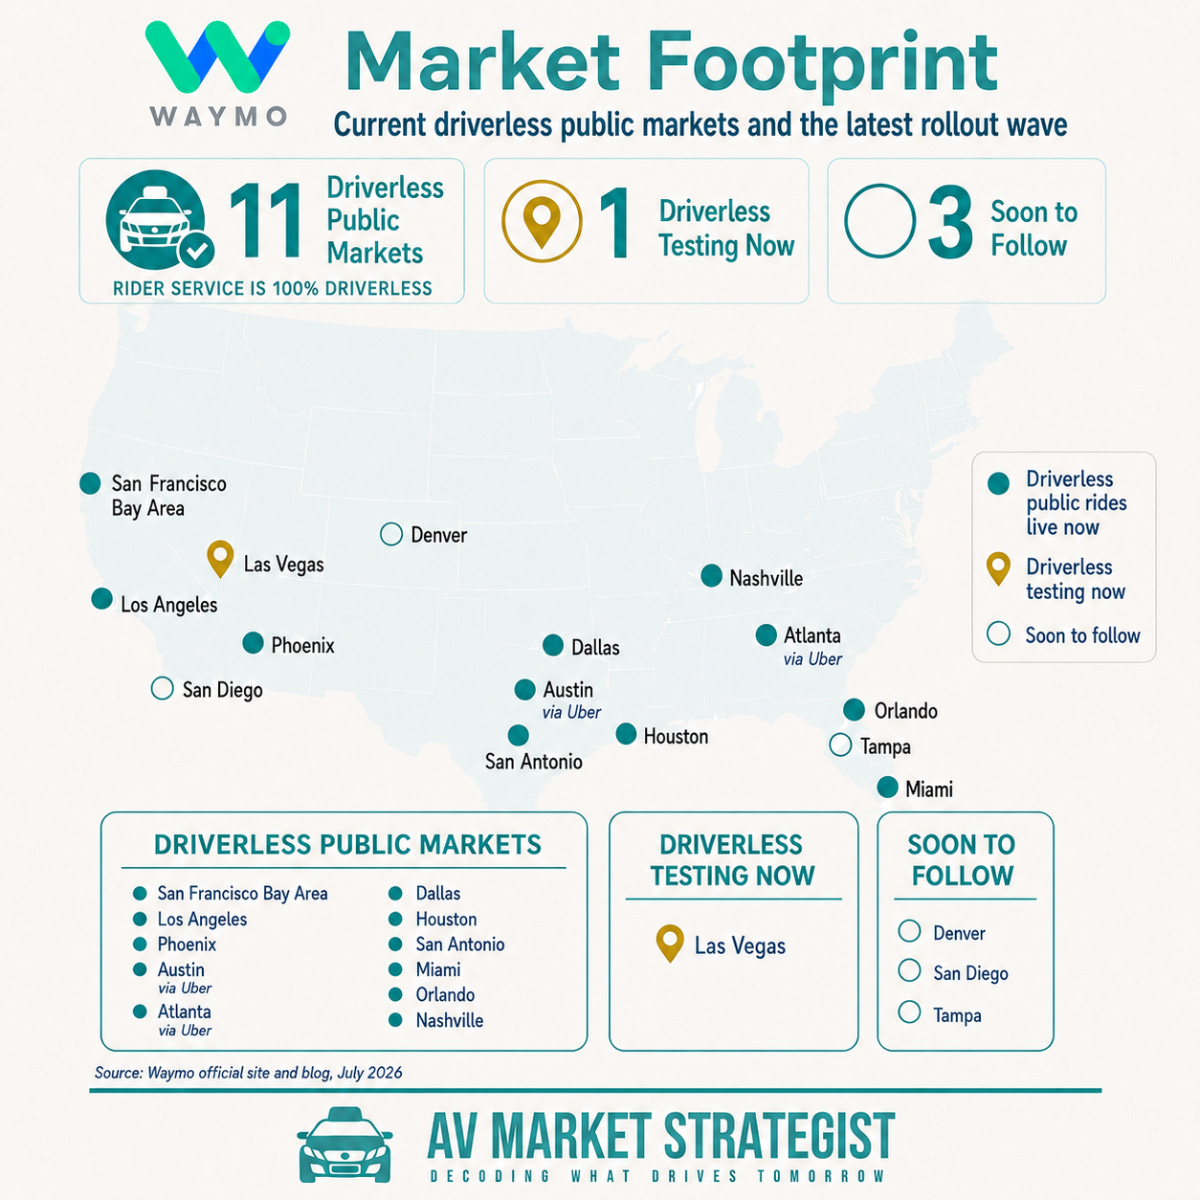
The scale behind the announcement: roughly 4,000 robotaxis, more than 20 million trips completed, and around 500,000 paid rides per week earlier this year, against a stated target of 1 million weekly rides by the end of 2026, with London to follow as the first international market.
Two details in the list deserve more attention than the headline. Denver is Waymo’s first snow-and-ice market. Every previous launch city is warm and dry, so this is the first time the “generalizable driver” thesis meets a real winter. And Tampa was not on the previously disclosed 2026 target list. Waymo is adding cities while executing on the existing ones.
The market leader keeps extending its lead. That is the first half of Waymo’s week.
The night the batteries died
The second half came on the 4th of July. After the fireworks over the Golden Gate Bridge, San Francisco’s streets filled with more than 100,000 people, unplanned road closures, and gridlock. Caught in the middle: Waymo’s fleet. NBC News verified footage of at least a dozen stationary Jaguar I-PACE vehicles lined up on a single street, hazards flashing. Several idled in standstill traffic until their batteries were depleted and had to be towed away on flatbeds. One passenger described her Waymo continuing to drive while someone set off fireworks in the middle of the road. Another vehicle drove over fireworks and caught fire. No injuries were reported, and Waymo says its roadside assistance team worked to clear the vehicles while it evaluates “ways to strengthen Waymo’s resilience in major traffic disruptions.”
If this sounds familiar, it should. In December, a power outage that darkened traffic lights across San Francisco produced a similar scene of paused Waymos at dead intersections. Same city, same failure class: not the driving, the operating. The vehicles did not crash. They ran out of energy, connectivity, and options, in a situation every local human driver knew to avoid.
Washington’s warning
Loyal readers and industry followers know these were not Waymo’s only difficult headlines in recent months. The flooding recall, the construction-zone recall that pulled the entire fleet off freeways, and the school-bus incidents all belong to the same file. This week, that file landed on a federal desk.
On July 8, NHTSA Administrator Jonathan Morrison sent AV developers what he called a “call to action,” citing a “clear pattern of driverless AVs interfering with law enforcement and other first responders”: vehicles driving into active emergency scenes, blocking ambulances and firefighters, failing to respond to flashing lights, flares, smoke, and traffic cones. Two lines are worth quoting in full. “To state it bluntly: An AV that cannot safely interact with first responders is a danger to the general public.” And: “Emergency scenes are not rare or extreme ‘edge cases.’” Developers are expected to present their fixes in meetings with the agency by the end of July.
The letter names no company. It does not have to. Read against the reporting of recent months, fire chiefs describing blocked stations, and a robotaxi delaying an ambulance for two minutes during a mass-shooting response in Austin, it is hard not to see Waymo among the primary addressees. To be fair, the pattern language deliberately covers the whole industry, and Zoox has had its own recall for stopping in front of oncoming traffic.
Let me be clear about where I stand. Vehicles that block ambulances are not acceptable, full stop, and the companies involved need to fix this quickly. At the same time, we should not let the worst scenes define the technology. Imperfect as it is today, autonomy is on a path to removing an enormous amount of human-caused harm from the roads. Both of those statements are true at once, and this week produced the best evidence yet for the second one.
The benchmark defense
Because here is the timing that makes this week remarkable: one day before Morrison’s letter, and three days after the fireworks, Waymo released two new studies, peer-reviewed and accepted for publication in Traffic Injury Prevention, built with researchers at the Virginia Tech Transportation Institute. Whether by design or coincidence, Waymo answered its worst operational week of the year with data rather than messaging.
The studies attack a problem we have written about repeatedly: comparing AV safety to “the average human driver” is easy, and mostly meaningless. Risk is not evenly distributed. On surface streets, human drivers in Memphis are involved in fatal crashes at 8.4 times the rate of drivers in Boston, so a single national average overstates Boston’s risk roughly threefold and understates Memphis’s by the same margin. Surface streets carry a fatal crash rate 2.3 times higher than freeways.
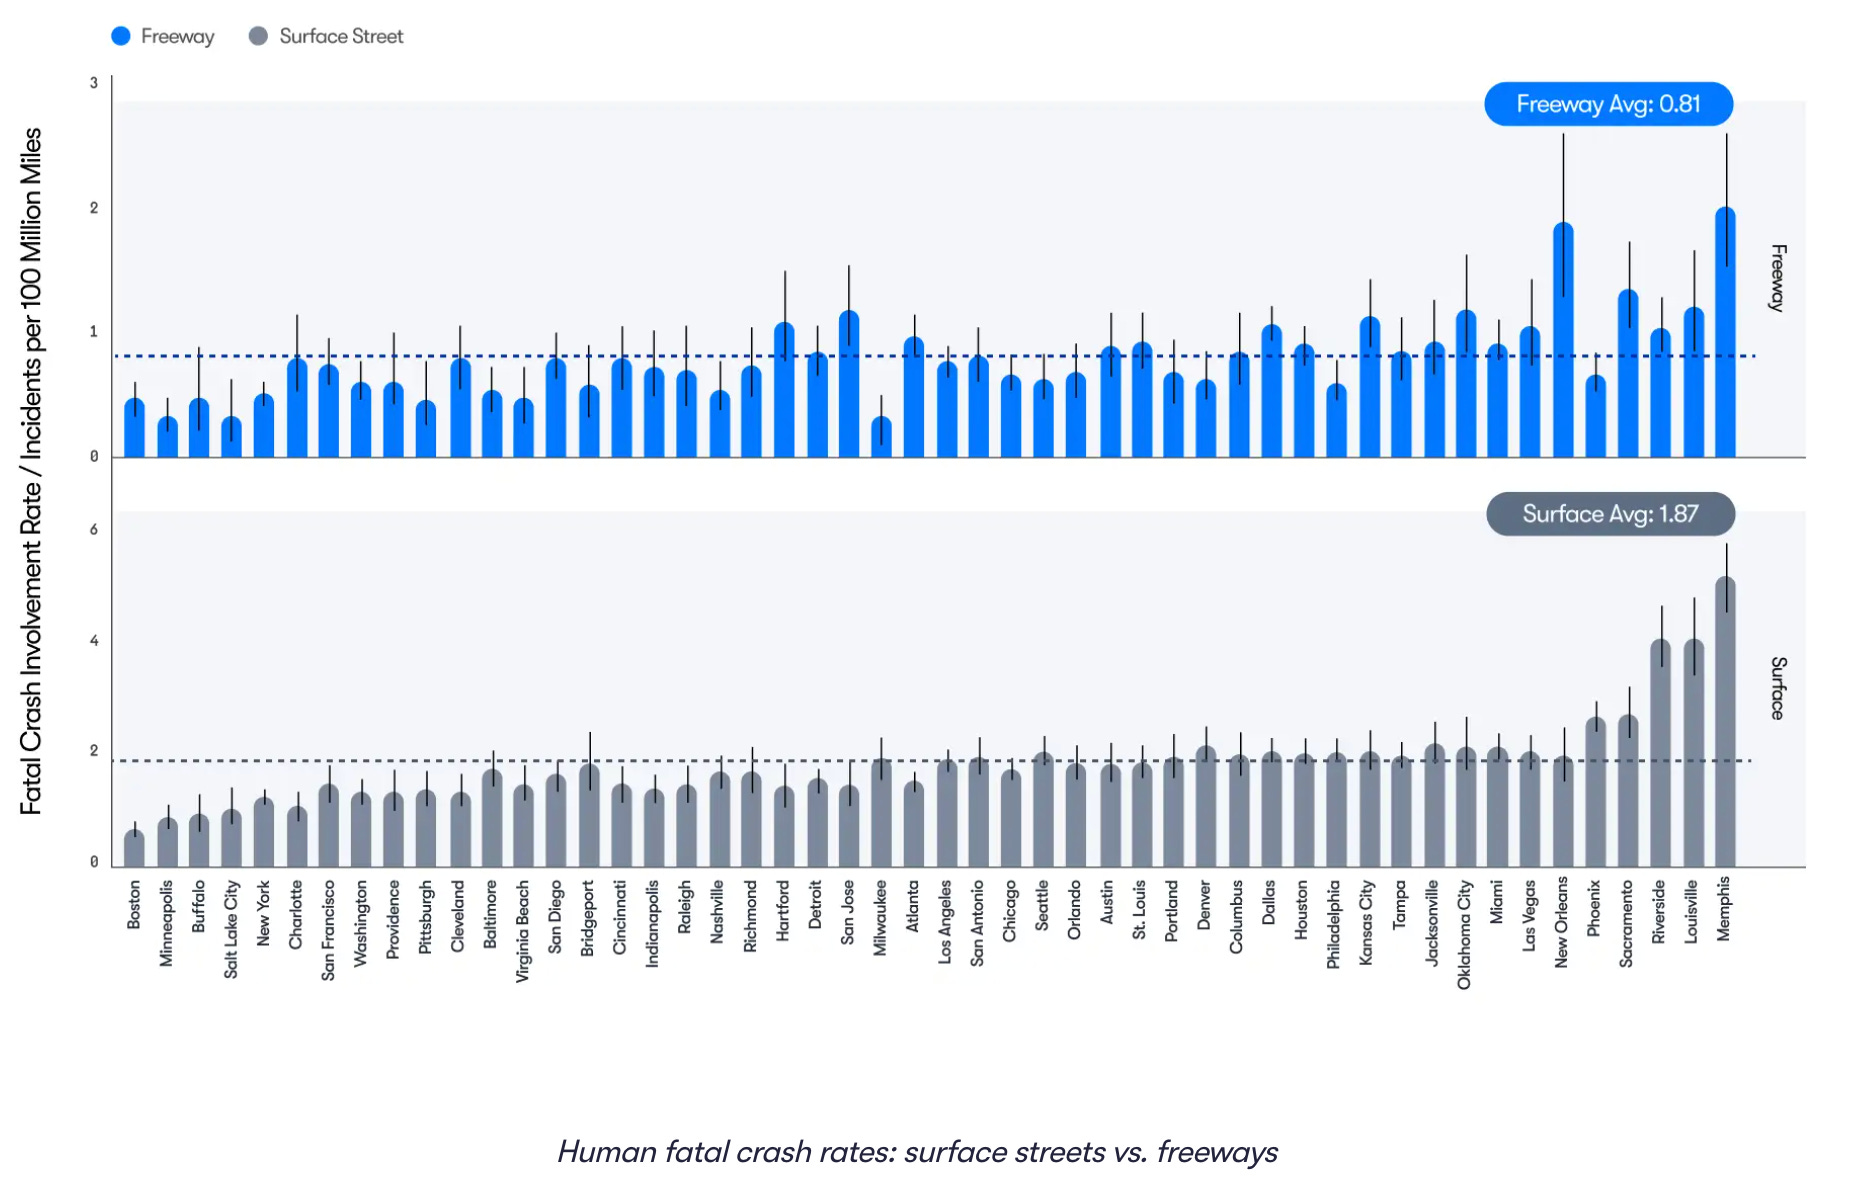
Source: Waymo
And risk shifts by the clock: between midnight and 4 AM, human crash rates run 2 to 6 times above the daily average, driven by fatigue, darkness, and impaired driving, hours that almost vanish in aggregate statistics because they account for just 1.5% of human mileage.
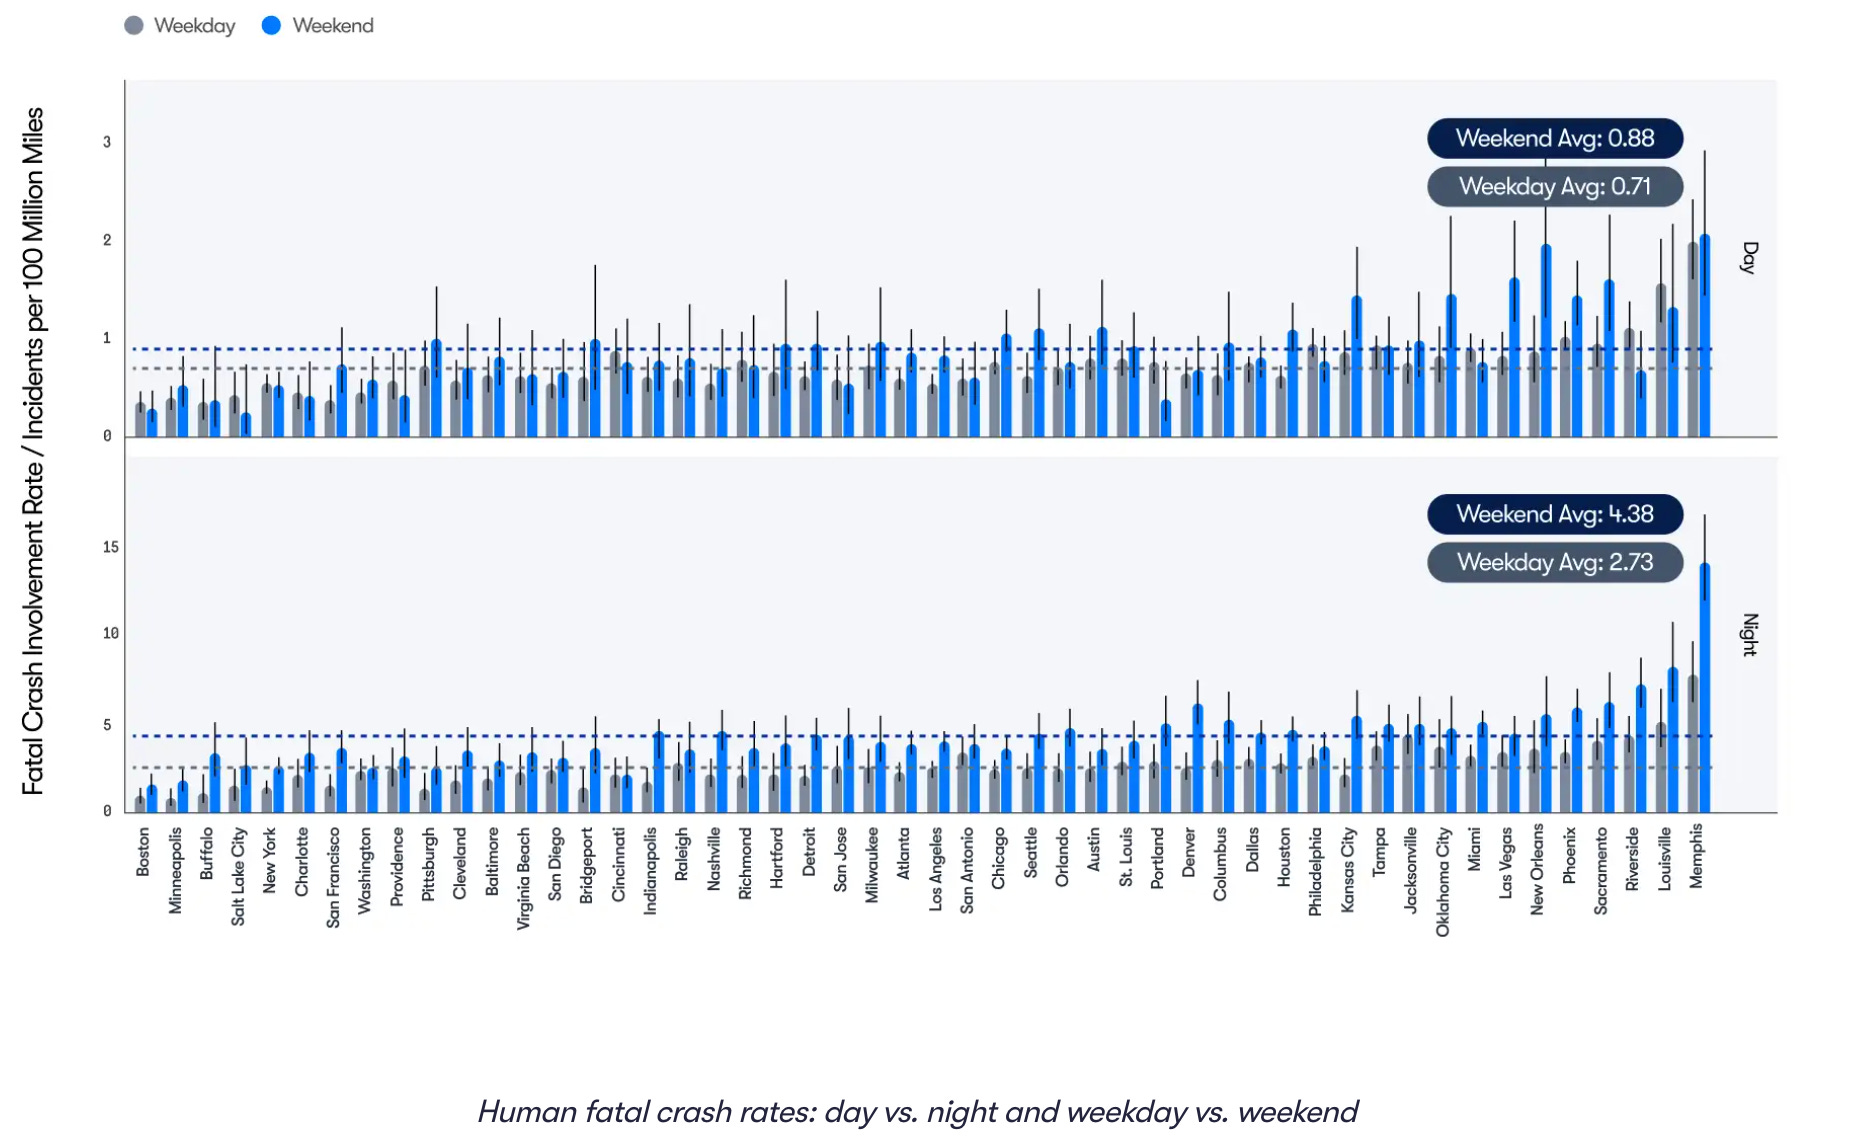
Source: Waymo
That last point matters for Waymo specifically, because its fleet drives proportionally four times more overnight miles than the average human driver. Measured against time- and location-matched human benchmarks across 127 million autonomous miles, the fleet was involved in 359 fewer injury crashes than comparable human driving, and 53% of that benefit came during the overnight hours when human risk peaks. In other words: judged on the hardest miles, the ones it deliberately seeks out, the system’s advantage grows.
Brad Templeton’s analysis adds the regulatory frame, and it is the right one. Companies default to nationwide comparisons because they are easier and they flatter. Regulators should not accept them. Their job is not to prevent every individual incident but to favor what demonstrably reduces total risk on the roads. And Templeton states the uncomfortable arithmetic plainly: at 500,000 rides per week, Waymo will make mistakes constantly, forever, in growing absolute numbers even as the rate improves, because perfection is not on the table. The questions that matter are whether the rate is improving, whether there are regressions, and whether the residual risk stays within what we already tolerate from human drivers, which is a great deal. Transparency of this kind is regulatory currency.
Which brings us to the operator that has historically done the opposite. Tesla’s best-known safety statistic compares airbag-deployment crashes in Teslas against police-reported crashes for all cars, the basis of the famous “10x safer” claim. Templeton notes that Tesla’s own data supports something closer to 1.5x, which is not nothing, but is not 10x. That contrast makes what Tesla did this week doubly interesting.
Tesla goes unsupervised in Miami
Over the Independence Day weekend, Tesla launched its Robotaxi service in Miami, its first unsupervised market outside Texas. The service area covers roughly 14 square miles in the city’s west, Doral and Coral Gables rather than downtown, Miami Beach, or the airport terminals. Two vehicles served rides on launch day, three by day three. For scale: Waymo, which went driver-out in Miami last November and opened service earlier this year, operates a Miami footprint roughly ten times larger.
The more telling part is how Tesla launched. According to The Information, Miami is the first market Tesla opened without safety monitors in passenger seats for early rides, and with substantially leaner pre-launch testing than Austin, where more than 300 drivers tested the service for weeks. Some testing staff were shifted to collecting training data instead. This is the test of Musk’s thesis that Robotaxi can expand fast without the market-by-market preparation that characterizes Waymo’s playbook. Recall the promises this launch is measured against: eight metropolitan areas by the end of 2025, which became four cities, and, per the April earnings call, a dozen states by the end of 2026.

Credit where due: the early rides look strong. Road to Autonomy’s field report from launch weekend (linked in Worth Watching below) called Miami the smoothest unsupervised Tesla ride across the three markets they have tested. Two details stand out. The vehicle pulled over and came to a complete stop for an ambulance running sirens, exactly the behavior Morrison’s letter demands, and worth noting in a week when the industry was scolded for the opposite. And it crossed flooded streets at a careful 8 mph without hesitating, in the kind of tropical downpour that NHTSA’s open engineering analysis of camera-only perception is asking about. The Road to Autonomy team also counted 21 Cybercabs with Florida license plates staged in a lot near Miami International Airport. Two or three cars serving passengers, dozens staged behind them: the ramp is being prepared, whether or not it has begun.
In CW28 we set up a test for the two camps in the Tesla debate: if the federal hardware rules land and the fleet ramps, the regulation-gated camp is right; if the rules land and the fleet stays flat, safety was the constraint all along. This week both camps collected evidence. The rulemaking is moving (more on that below), and Tesla’s registered fleet in Texas jumped from 42 vehicles in early June to 102, per state DMV data, against Waymo’s 642. The test is still open. Our lean from last week stands, safety first, because Musk said it himself, but 42 to 102 in five weeks is the first fleet growth we have logged after weeks of stagnation, and it deserves to be recorded.
One rule loosens, another tightens
On the regulatory side, the week brought Tesla both kinds of news. In New Jersey, lawmakers are advancing S1677, which would require driverless commercial vehicles to carry cameras plus two additional sensor types, in practice radar and lidar, along with 50,000 supervised in-state test miles, full crash reporting, and state authorization before any commercial launch. Sponsor Andrew Zwicker, a physicist, insists: “This is not anti-Tesla. I’m pro-New Jersey safety.” Taken at face value, he is right, the bill targets an architecture, not a company. Any camera-only system is out. It just happens that only one operator of consequence runs camera-only. The bill also favors traditional controls like steering wheels and pedals, which would exclude the Cybercab, and New York is considering nearly identical language.
There is a serious counterargument, and it is worth airing. Walter Piecyk calls sensor mandates the wrong instrument entirely: legislating which hardware a vehicle must carry is like regulators picking GSM over CDMA in the early wireless days, prescribing the technology instead of the outcome. Harry Campbell of The Driverless Digest made the same point when Lyft announced it would require multi-sensor redundancy from the AV partners on its platform, a story we covered in CW27: “I’d rather see an outcome-based framework that judges systems on real-world safety performance, not the specific technology or sensor stack they use.” I agree with that view, not least because an outcome-based framework needs exactly the kind of localized, time-matched performance data Waymo published this week. The catch is sequencing: until every operator publishes that data, hardware rules are what legislators reach for. New Jersey is now writing into law what Lyft already wrote into its commercial terms.
The bigger news for Tesla points the other way. NHTSA Administrator Morrison said this week the agency will “absolutely” consider ending the requirement that driverless cars carry steering wheels. His reasoning: “If you’re developing a vehicle that is designed never to be driven by a human operator, it doesn’t make any sense to require manual controls.” This follows directly on the brake-pedal proposal we covered in CW27. For purpose-built vehicles, Tesla’s Cybercab, which entered engineering tests of production units at the end of June, and Zoox’s robotaxi, this is the federal hardware wall coming down piece by piece, at the same time as individual states begin building sensor walls of their own.
What this means and what to watch
Transparency is becoming the price of scale. Waymo’s time- and location-matched benchmark will not stay a research artifact. It is now the reference methodology, and operators who publish first get to define the metric everyone else is measured by. The ones who keep citing flattering averages will find regulators doing the localized math for them.
Special events are about to become a permit condition. Two city-scale failures in the same city within seven months is the kind of pattern regulators act on. Expect event-preparedness plans, and questions about what happens to passengers in a stalled fleet, to enter the approval process in California first and spread from there.
The US regulatory map is splitting in two. Washington is deleting hardware mandates while New Jersey and New York start writing them. For camera-only architectures, the state patchwork, not NHTSA, is now the larger deployment risk in exactly the dense coastal markets a robotaxi business eventually needs.
Watch the end of July. NHTSA wants solutions on first-responder interaction from every developer within three weeks. What the companies bring to those meetings, and whether they disclose it publicly, will tell us who has internalized the transparency lesson and who has not.
🔗 Electrek / CNBC / NBC News / WIRED / TechCrunch / Waymo / Forbes / The Information / Electrek / Bloomberg
Enjoying the AV Market Strategist?
If you find value in these deep-dives and enjoy the updates on autonomy each week — you can support my work.
Your contribution helps me access better data sources, industry reports, and research tools to keep every issue sharper and more insightful.
The newsletter will always remain free to read, whether you choose to support or not — but every bit of backing helps me make it even better.
THE TESLA-SPACEX MERGER QUESTION
Now to my favorite recurring Tesla topic, one we have discussed here several times before: a potential Tesla-SpaceX merger. So far this thread has lived inside other stories, a paragraph here, a signal there. This week brought enough new material that I’m giving it a full section of its own. When Musk starts talking about convergence, history suggests he means combination.
A decade ago, Musk himself saw little reason for the two companies to merge, calling the ties between them “really quite tenuous.” Lately his language has shifted: he increasingly describes a “convergence” across the parts of his business empire. And as we reported in CW25, SpaceX’s IPO filing carried a warning that it may issue “a significant amount of equity in connection with future transactions,” which did nothing to calm the speculation.
And this is no longer just outside chatter. CNBC reported in the run-up to the IPO that Musk has discussed folding the two companies together with colleagues, and that at Tesla the topic is discussed openly, with many employees having long expected the transaction to eventually happen.
At first glance, the two companies still look unrelated. One builds electric vehicles, the other launches rockets and satellites. Bloomberg’s analysis names the common denominator: artificial intelligence. Tesla has bet its valuation on autonomous driving and humanoid robots. SpaceX absorbed xAI in February and wants data centers in orbit; Bloomberg Intelligence modeling has AI becoming SpaceX’s biggest revenue source from this year on.
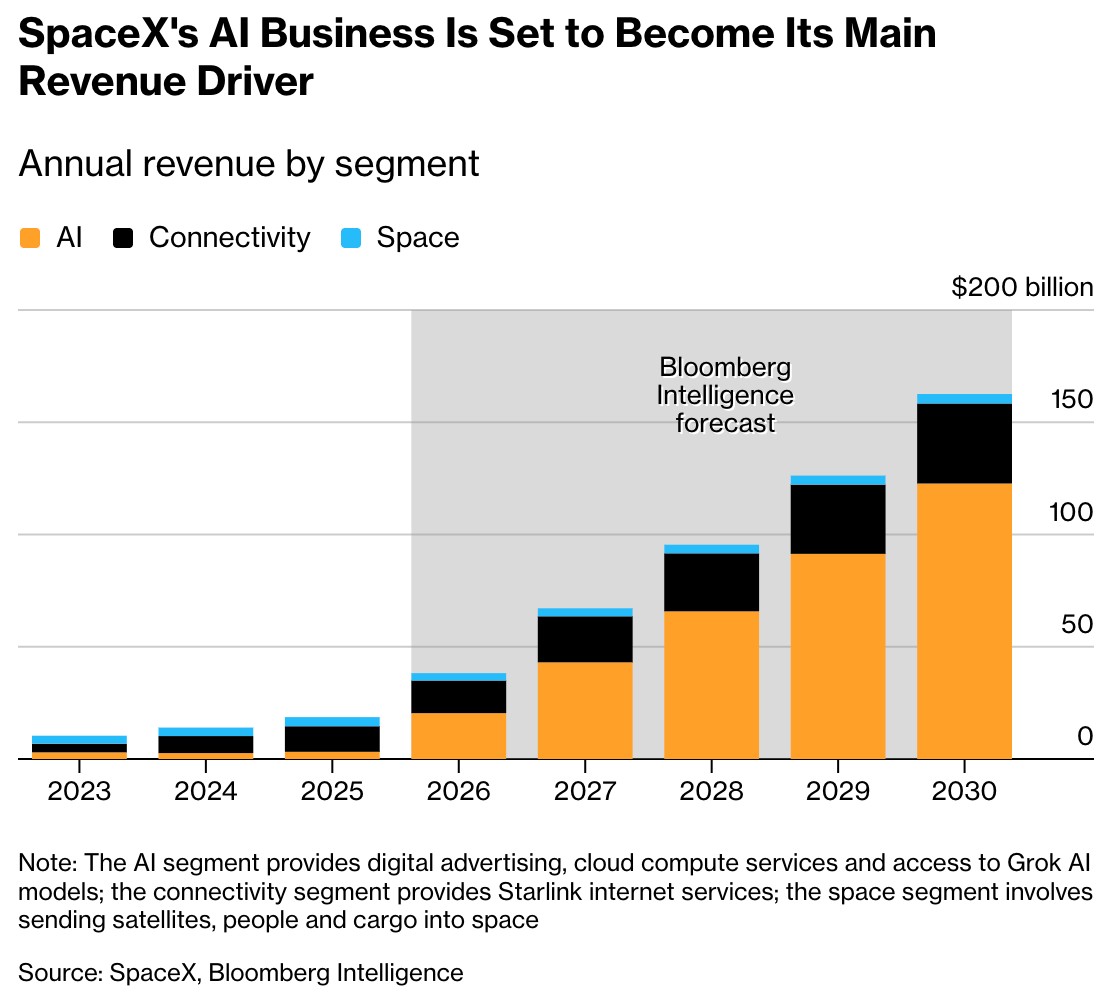
Source: Bloomberg
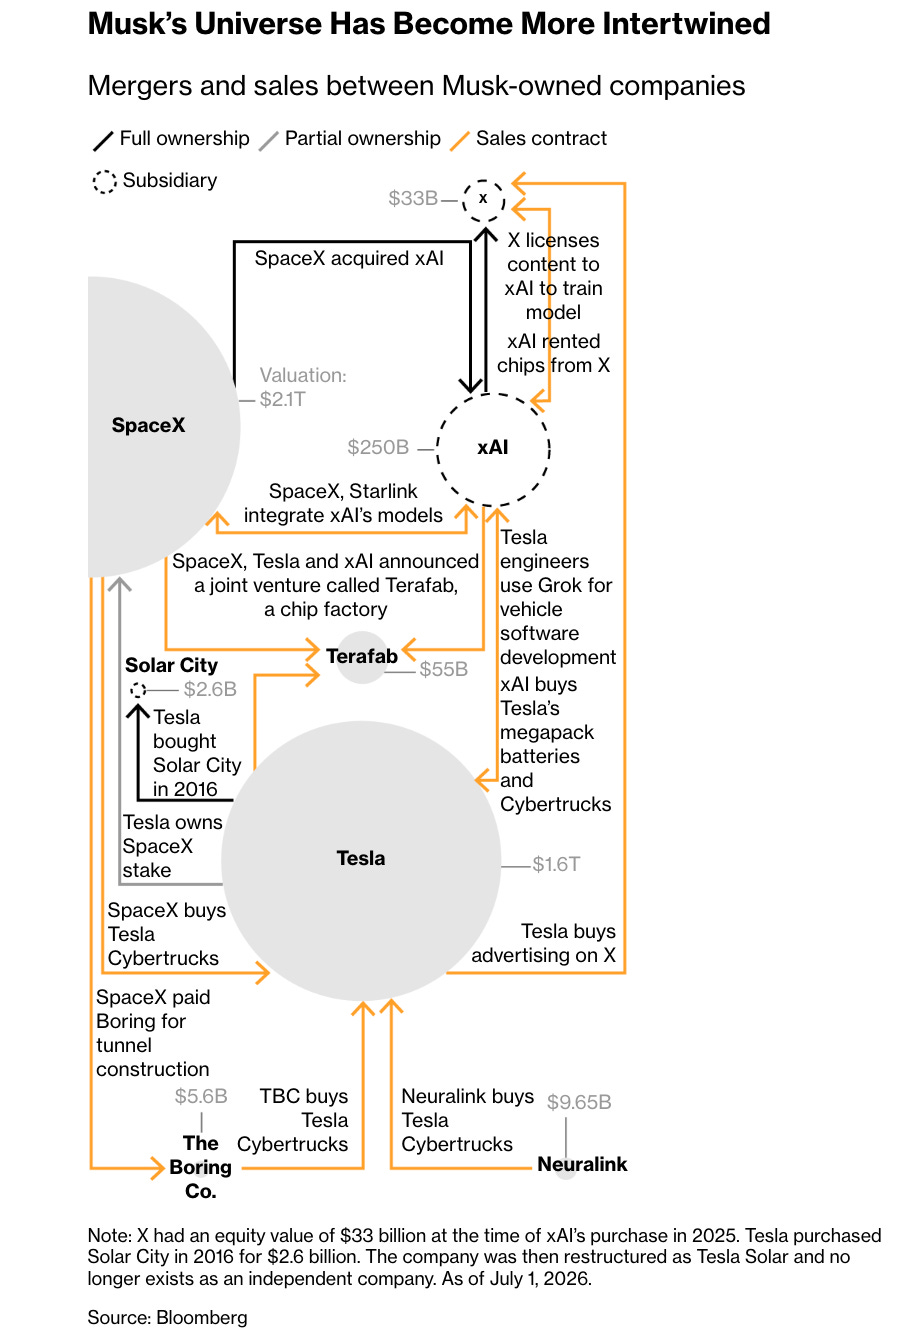
The once-tenuous links have hardened into infrastructure. SpaceX mentioned Tesla by name 88 times in its amended IPO filing, has spent more than $1 billion on Tesla utility-scale batteries to power xAI data centers, and bought $131 million worth of Cybertrucks. Tesla, in turn, holds a SpaceX stake after its $2 billion xAI investment converted in March. Add the planned Terafab chip plant, meant to produce semiconductors for Tesla’s vehicles and robots and for SpaceX’s orbital AI satellites, and the “no overlap” argument is gone.
The overlap runs through people and suppliers too: Musk sits on both boards alongside investor Ira Ehrenpreis, one executive serves as vice president of materials engineering for both companies at once, and in 2024 Nvidia diverted a $500 million GPU order from Tesla to xAI at Musk’s request. Suppliers already treat the empire as one customer.
That explains collaboration. It does not yet explain acquisition. Why merge instead of simply continuing to work together? I see four reasons, and they stack.
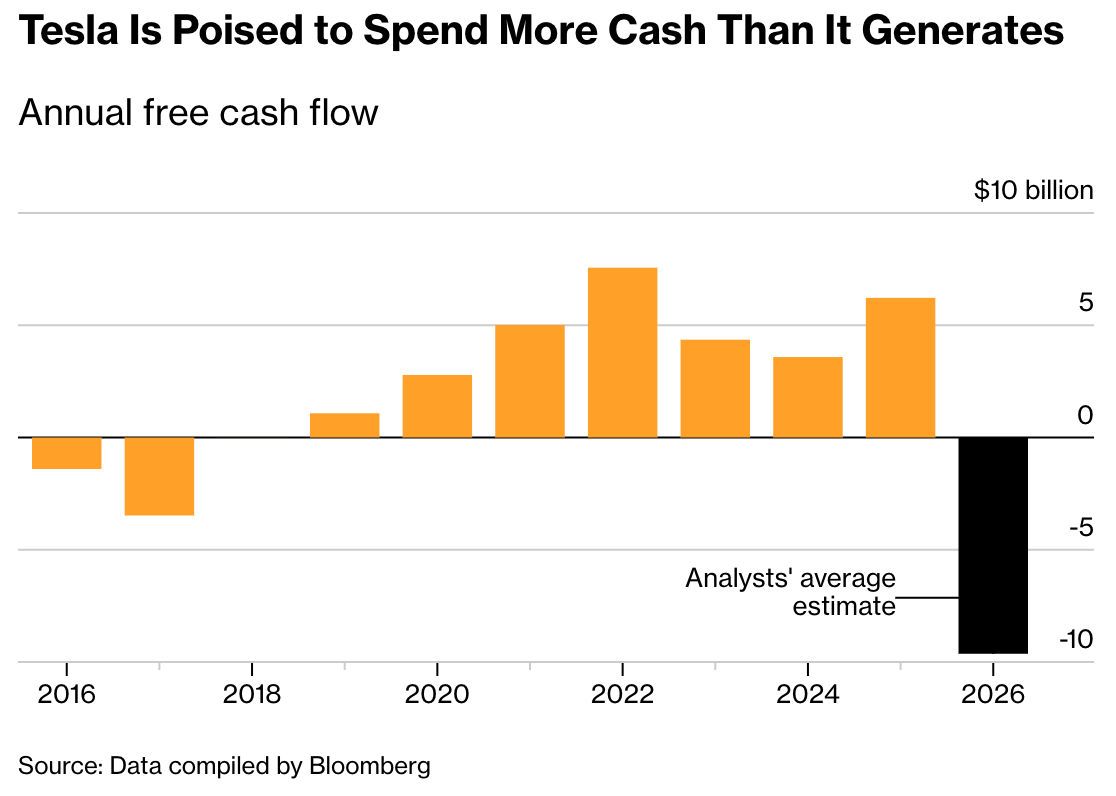
1. AI needs enormous amounts of capital, and Tesla’s cushion is thinning. Neither company has ever struggled to raise money, and Tesla has long been the cash-generating half of the empire. But the spending on its futuristic bets is catching up: analyst consensus now sees Tesla’s free cash flow turning negative in 2026 for the first time since 2018, and by a wide margin.
Source: Bloomberg
Meanwhile, xAI was burning around $1 billion a month as recently as a year ago. And with SpaceX now publicly traded, Tesla is no longer the only stock through which investors can own the “Musk factor.” A combined entity could borrow and raise at a scale neither can alone.
2. The divided-attention complaint disappears. Shareholders have grumbled for years about Musk juggling ventures. A merger dissolves the complaint by definition. SpaceX President Gwynne Shotwell said as much in the run-up to the IPO, as we noted in CW25: a combination would make life “easier” for Musk.
3. Musk has a track record of blending his companies, especially the struggling ones. Tesla absorbed debt-laden SolarCity in 2016. After the Twitter acquisition drove away users and advertisers, X was folded into xAI, which gave the platform a new purpose without Musk ever having to concede the failure. Loss-making xAI was then itself combined with SpaceX in February. The empire has become a fully interwoven web, and consolidation is, in part, how Musk prevents any single bet from being seen to fail.
Source: Bloomberg
4. Control. Musk holds roughly 20% of Tesla, with a single share class. At SpaceX, a dual-class structure gives him 42% of the shares but more than 80% of the voting rights. In a combined entity, he could finally secure the majority control over the Tesla side of his empire that he has wanted for years.
Seen this way, a merger is less a standard acquisition than Musk resolving the governance anomaly in his own empire: today he must persuade Tesla shareholders on every major decision, at SpaceX he does not. A combination executed on SpaceX’s terms would flip him from minority voting power at a $1.5 trillion company to majority control of one worth close to $4 trillion. RBC makes the same point from the shareholder side: part of the premium it models is compensation for Tesla holders surrendering exactly that control.
The mechanics favor Elon: under Texas law a merger needs two-thirds shareholder approval, which Musk can deliver single-handedly at SpaceX, and while he cannot do the same at Tesla, retail holders have a long history of voting with him. Blocking options for dissenters are thin; since the move to Texas, shareholders need at least 3% of the stock even to file a derivative suit, a bar almost no institution clears alone.
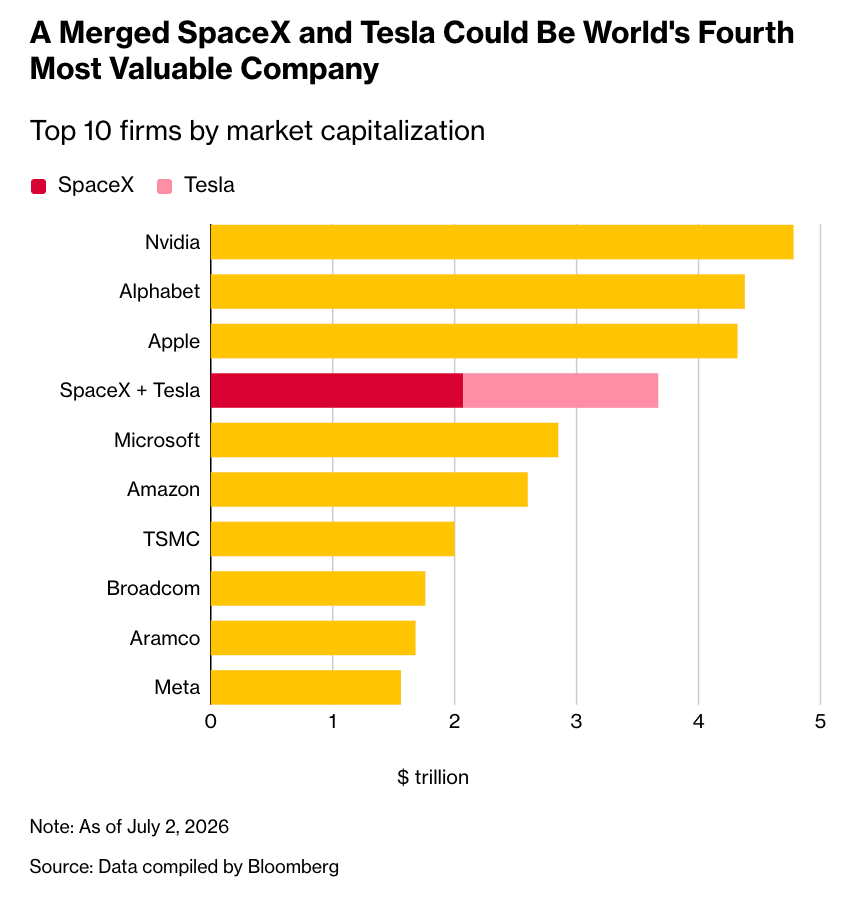
What would a combination be worth? At early-July market caps, close to $4 trillion, which would make it the world’s fourth most valuable company behind Nvidia, Alphabet, and Apple.
Source: Bloomberg
That said, conglomerates often trade below the sum of their parts, and a SpaceX-Tesla entity spanning rockets, cars, robots, and data centers would be a prime candidate for exactly that discount. A deal would also invite national-security scrutiny, SpaceX is a major defense contractor while Tesla manufactures at scale in China, though antitrust approval is likely easier under the current administration than any plausible successor.
And Wall Street has stopped treating the idea as fan fiction. RBC has formally built a 25 to 30% SpaceX acquisition premium into its Tesla price target, arriving at $500 against a standalone value of $435. Dan Ives at Wedbush puts the probability of a merger within the next year above 80%, and JPMorgan calls the idea “strategically coherent on paper.” Prediction market Kalshi currently puts the odds of a combination before 2028 at 70%.
My personal read: it is fairly clear to me that Musk will attempt this. Working through the motives, capital, attention, consolidation instinct, and above all control, I find too many reasons for him to try and too few for him to wait indefinitely. What I cannot tell you is when. Until a filing says otherwise, this remains speculation, and I am comfortable labeling it as such.
What this means and what to watch
July 22 is the near-term test. Tesla reports Q2 earnings, and after a quarter in which record deliveries were answered with the stock’s worst rout in a year, the market has made its priorities explicit: it wants evidence that robotaxi and storage are moving from narrative to numbers. Deliveries no longer set the price. The merger question and the autonomy ramp do.
Watch SpaceX’s equity moves. The S-1 warning about issuing “a significant amount of equity in connection with future transactions” was the first tell. A large issuance, or any structure resembling an acquisition currency, would be the second.
🔗 Bloomberg / Bloomberg (2) / Bloomberg (3) / CNBC / INDmoney
💡 Quick Takes
Forterra’s autonomous ATVs have been fighting in Ukraine for nine months
More than 100 self-driving Lancer vehicles have driven 2,500+ miles across 1,100+ missions, carried 777,440 pounds of cargo, and completed 88 casualty evacuations, the largest combat deployment of autonomous ground vehicles by any US defense tech company.
🔗 TechCrunch
Ukraine’s National Guard will test German autonomous logistics
Quantum Systems signed a multi-million-dollar contract to deliver 10 autonomous Zetros trucks (built with Daimler Truck Defense) and 10 MANDRILL unmanned ground vehicles, each carrying 750+ kg over 200 km per charge, for field trials.
🔗 Defence Express
The Port of Felixstowe is expanding its autonomous truck fleet to 100 vehicles
Britain’s busiest container port ordered a third batch from Shanghai’s Westwell, making it Europe’s largest deployment of autonomous trucks in live, mixed-traffic terminal operations. The fully electric fleet runs on a private 5G network and swaps depleted batteries for charged ones in five to six minutes, and it is worth noting who supplies it: a Chinese AV company scaling inside UK critical infrastructure.
🔗 AJOT
Singapore is putting $800 million into transport research over five years
About two-thirds targets autonomous systems and digital twins, including new testing and certification frameworks for AVs, another data point that the city-state intends to stay Asia’s most structured AV environment.
🔗 The Straits Times
XPeng’s robotaxi closed beta is live, and the CEO took ride number one
He Xiaopeng hailed the company’s first internal robotaxi ride in Guangzhou. The vehicle runs a camera-only stack with 3,000 TOPS of in-house Turing compute, no lidar, no HD maps. Pilot operations are planned for H2, driver-free daily operation for early 2027.
🔗 CNEVPost
Germany gets a dedicated AV fleet operator
CleverSolutions, the team behind the former CleverShuttle, launched CleverSolutions Autonomous to run AV fleets on behalf of transport operators and municipalities, funded by two Bavarian bus companies. The operating layer keeps professionalizing.
🔗 Zag Daily
Autolane is running restaurant deliveries in Austin with 13 Tesla Model Ys
Miami and Los Angeles are next. The startup builds “air traffic control” for private curbs, coordinating AVs, delivery bots, and drones at shopping centers, in a last-mile autonomy market Statista sees growing from $26.6 billion to $50+ billion by 2028.
🔗 EVwire
Germany wants 10,000 autonomous public transport vehicles by 2030
The INIT-led BRAVE10k project, backed by TÜV Rheinland, the federal economics ministry, and ~20 partners, will build the tendering, approval, and certification framework to get autonomous shuttles past pilot scale.
🔗 Automotive World
Japan’s Turing added AMD as backer and supplier
The Tokyo startup raised a $79 million Series A extension (~$600 million valuation) with AMD Ventures participating, and now runs about 10% of its AI training on AMD GPUs to diversify away from Nvidia, targeting consumer autonomy and robotaxis by 2028.
🔗 Bloomberg
Wayve’s employee share sale found its buyers
The $85 million tender we covered in CW28 cleared at a 10% discount to February’s $8.6 billion valuation, with Ark Invest, G Squared, Liberty Street, and Launchbay leading, the most significant transaction yet on London’s new Pisces private market.
🔗 Bloomberg
🎧 Autonomy Insiders
The autonomous driving industry has mostly converged on one architecture: a single, monolithic end-to-end model trained to handle the entire driving task.
Igal Raichelgauz, founder and CEO of Autobrains, argues that approach hits a wall on edge cases and compute cost.
His alternative is “agentic AI.” Driving is broken into a large but finite set of specialized agents, each an expert in a specific situation, invoked by an orchestrator in real time. Autobrains claims this runs on roughly an order of magnitude less compute, needs almost no labeling, stays vision-only, and skips HD maps.
📚 Worth Reading/Listening
Harry Campbell: Einride’s Autonomous Freight Strategy with CTO Henrik Green
🔗 The Driverless Digest
Tesla Unsupervised Robotaxi Miami Field Report
🔗 Road to Autonomy
📊 Weekly Performance
Note: Stock performance data as of July 12th, 2026. Past performance does not indicate future returns.
Thanks for reading!
If you found value in this newsletter, please consider sharing it with a friend or colleague who might benefit from these insights.
And if you haven’t already, subscribe to stay updated on the latest developments in the autonomous driving industry.
Disclaimer: This newsletter is provided for general informational and educational purposes only and is subject to change without notice. While we obtain information from sources we believe to be reliable, we do not guarantee its accuracy, completeness, or timeliness. We accept no responsibility for any actions taken based on this newsletter or for any losses resulting from its use. Nothing in this newsletter constitutes, or is intended to constitute, financial, investment, trading, legal, accounting, or tax advice. The content does not take into account your individual objectives, financial situation, or needs and must not be relied upon as personalized recommendations to buy, sell, or hold any security or other financial instrument. You should always do your own research and consult a licensed financial professional before making any investment decisions. Any opinions or views expressed in this newsletter are those of the authors at the time of publication and may change without notice. They do not necessarily reflect the opinions of any affiliated entities.
Safety should always be a priority. The industry must learn from past challenges to improve. Innovative partnerships can drive progress. Collaboration often leads to breakthroughs that benefit the entire sector.
Waymo's ability to prove its safety advantage with peer-reviewed data on high-risk overnight miles stands in sharp contrast to its operational vulnerability during the 4th of July gridlock, proving that while driving a robotaxi is largely a solved problem, operating a resilient fleet amid chaotic human environments remains the true bottleneck.