
👋 Welcome back everyone,
I am writing this from Bari, in the south of Italy, where I am on holiday with my family. The sea is twenty metres away but I was not going to let a week off stop me from getting you the news and my take on it, so here we are. Earnings season does not take a holiday either.
And this week Tesla reported.
Let’s dive in!
⏱️ ~7000 words, 30-minute read
AD

Why Charging Depot Location Is the Most Underrated Lever in AV Fleet Economics
Most AV fleet operators fixate on vehicle cost and energy price when calculating cost-per-mile. But there’s a bigger lever hiding in plain sight: depot location. Every mile a vehicle drives to reach a charger is a mile it’s not earning revenue.
Terawatt’s modeling shows optimized depot siting can cut deadhead miles significantly, unlocking tens of thousands in monthly margin per stall and reducing cost-per-mile by up to $0.10.
Tesla Q2 2026 Earnings: 3 New Cities, Minus $1.1 Billion Free Cash Flow, and a Cybercab Data Problem
Tesla spent the quarter proving it can open markets quickly. It spent the earnings call explaining why it cannot fill them.
The launch that arrived one day early
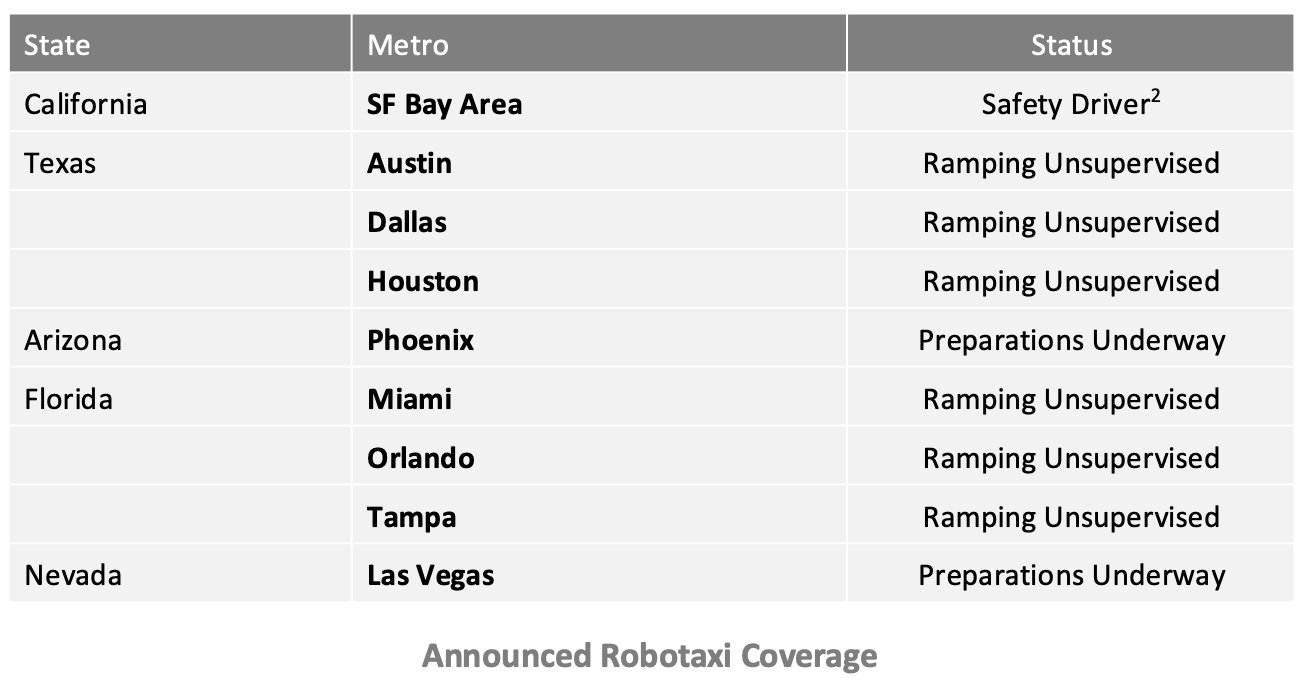
On Tuesday, one day before the Q2 earnings release, Tesla brought an unspecified number of unsupervised Model Y SUVs to Tampa and Orlando. That makes Florida the state with the most Tesla robotaxi markets, three, following the Miami launch a few weeks ago.
Source: Tesla Q2/2026 Investor Presentation
The timing is not subtle, and it is not new. Tesla announced autonomous fleets in Dallas and Houston shortly before its first-quarter earnings release and then did not meaningfully scale either one. The pattern has now repeated with a second pair of cities before a second earnings call.
The operating areas tell you more than the launch does. Both are small, and neither includes the airport, which was also true of Miami. That is the constraint worth tracking, because airport traffic is the most reliable and highest-frequency demand in any ride-hail market, and it is the first thing an operator goes after once it is serious about revenue.
Which sets the ceiling on what these launches can be. Until the service areas grow and the airports open, none of the three Florida markets is competition for Uber and Lyft. They are proof that Tesla can arrive in a new city quickly, which is a real capability, and a genuinely fast one. It is just not the same capability as running a business there.
The financials: demand came back, economics did not
Now to the quarter itself, because the market’s reaction was severe and the reasons are specific.

Source: App Economy Insights
Revenue was $28.2 billion, up 26 percent from $22.5 billion a year ago, and about $1.7 billion ahead of consensus. Automotive revenue was $20.5 billion against $16.6 billion. Deliveries came in above 480,000, up 25 percent year over year and roughly 74,000 above the company-compiled consensus, driven by records in South Korea, Australia, Japan, Taiwan, Portugal and a long list of smaller markets. Trailing twelve-month revenue crossed $100 billion for the first time. Tesla exited the quarter with its largest order backlog since 2023, and CFO Vaibhav Taneja said production is now the constraint, specifically batteries and electronic components.
That is a genuinely strong demand quarter. It is worth saying plainly, because the rest of this section is not going to be kind.
Below the revenue line, everything compressed. Operating income fell 57 percent to $398 million, roughly a quarter of what the street expected. Operating expenses rose 47 percent to $4.3 billion on research and development, pre-production ramp costs for Semi, Optimus and Cybercab, additional compute depreciation, and litigation charges. Automotive gross margin excluding regulatory credits fell from 19.2 percent to 16.3 percent.
Taneja’s defence of that margin number is fair and worth repeating, because this newsletter does not grade on narrative. Q1 included a $230 million warranty true-down and some tariff relief that did not repeat. Adjusting for those, underlying automotive margins were roughly flat. Rising commodity prices and rising interest rates did the rest, the latter through subvention costs that are booked upfront as a revenue offset. So the margin decline is more about a flattering Q1 than a collapsing Q2.
Net income was $1.1 billion, down 5 percent. That figure needs an asterisk in both directions: it includes a $1.0 billion unrealised mark-to-market gain on Tesla’s SpaceX holding, offset by roughly $300 million of FX losses and $100 million on Bitcoin. Strip the SpaceX gain and the quarter’s reported profitability is largely an accounting artefact of an investment in a private company Tesla does not control.
The quiet bright spot was services: revenue up 50 percent to $4.6 billion, gross margin from 9.2 percent to a record 14.1 percent. Taneja noted something easy to miss in that line, that the segment also carries “deliberate investments we are making in infrastructure that will help scale Robotaxi in the future.” The depot, charging and fleet-support layer is being built inside a segment nobody watches.
Then the cash. Capital expenditure more than doubled sequentially to $5.8 billion, up 142 percent, pushing free cash flow to negative $1.1 billion against positive $1.44 billion last quarter. Consensus had expected negative $3.3 billion, so on the narrow question of cash burn Tesla beat.

Source: App Economy Insights
The forward math is heavier. Capex guidance stays above $25 billion for the year and only $8.3 billion went out in the first half, implying at least $16.7 billion in the second, more than double. Taneja said capex keeps growing for another two or three years, and confirmed debt facilities providing borrowing capacity of up to $30 billion. Tesla still holds $43.5 billion in cash. But a business that funded its own expansion for a decade is now adding leverage to the plan.
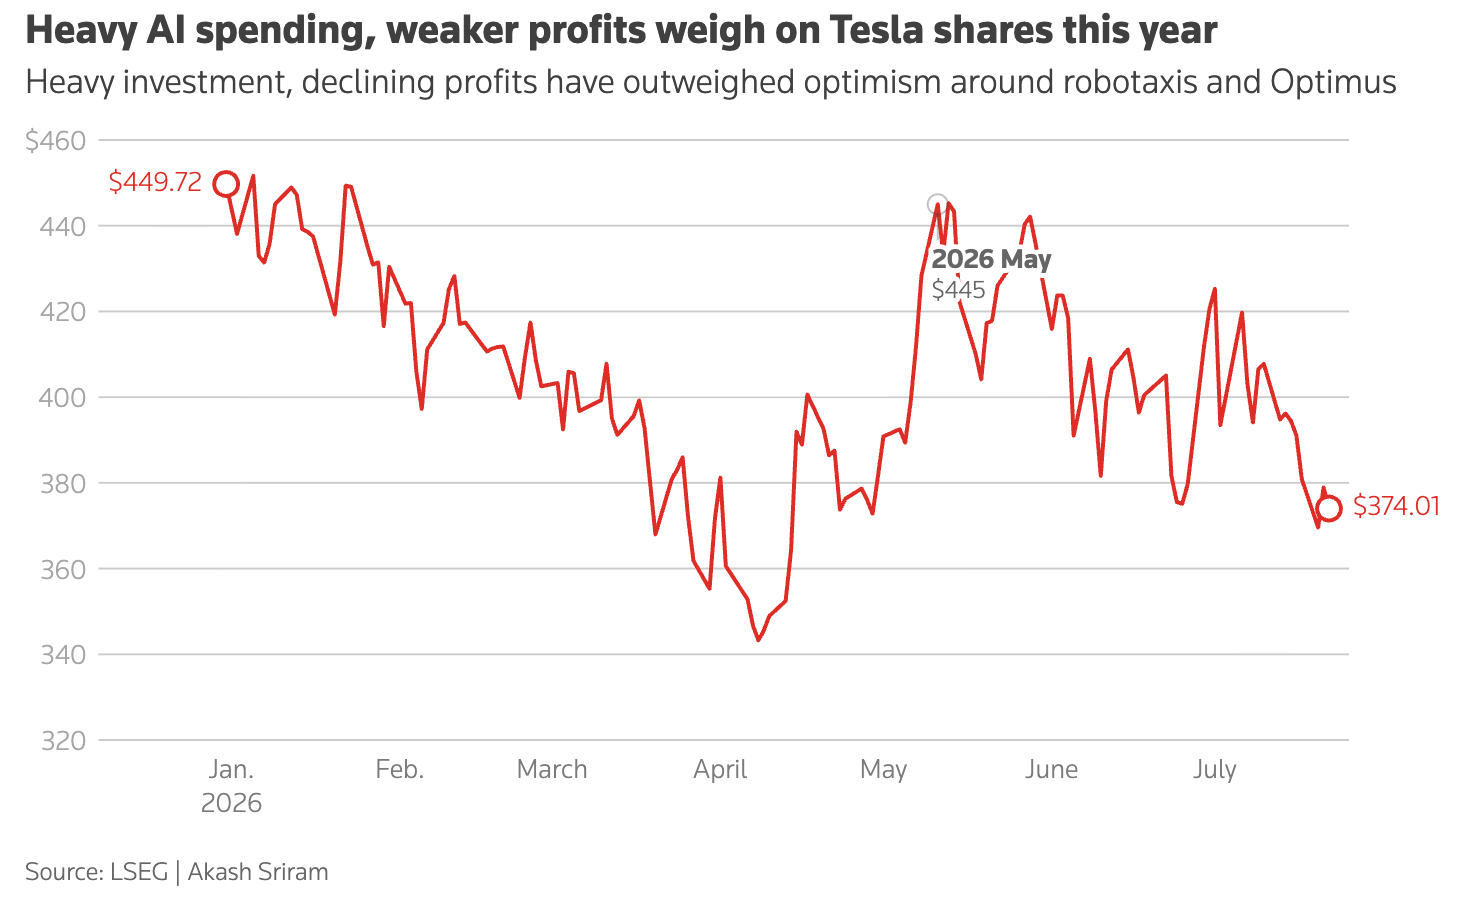
The market’s verdict was immediate: the stock fell roughly 14 percent, its worst post-earnings decline since 2013. That reaction is rational rather than emotional.
Source: Reuters
Tesla is asking investors to fund more than $16 billion of second-half spending on the promise of robotaxi, Optimus and AI infrastructure, and in the same disclosure the robotaxi business drove fewer paid miles than it did three months earlier. The market is not rejecting the strategy. It is repricing the gap between the spending and the evidence.
The autonomy disclosures, and the one that changes the story
Now to the part that matters most for us in this newsletter.
Start with what is working. FSD reached nearly 1.5 million paid customers, up 56 percent year over year, and the mix has shifted decisively: 45 percent subscriptions against roughly 30 percent at the end of last year. With the upfront option removed in most markets, essentially every net addition now arrives as a subscriber. About 55 percent of North American Q2 deliveries had FSD enabled at delivery. Musk’s framing was that customers are “buying Tesla full self-driving with a car attached.”
Convert that into meaning. A one-time sale becomes a recurring line with a much longer tail, worse for near-term revenue and better for the business over time, and it turns FSD into a subscription base Tesla can upsell against later, connectivity included. This is the healthiest thing in the autonomy disclosure, and it has almost nothing to do with robotaxis.
Now the robotaxi numbers. Ashok Elluswamy, VP of AI, gave the bull case in prepared remarks: more than 380,000 unsupervised miles across six cities in two states, “zero notable incidents,” and week-over-week growth in unsupervised miles at double-digit rates that the company expects to sustain. His conclusion: “Robotaxi growth so far has been literally exponential while keeping an impeccable safety record.”
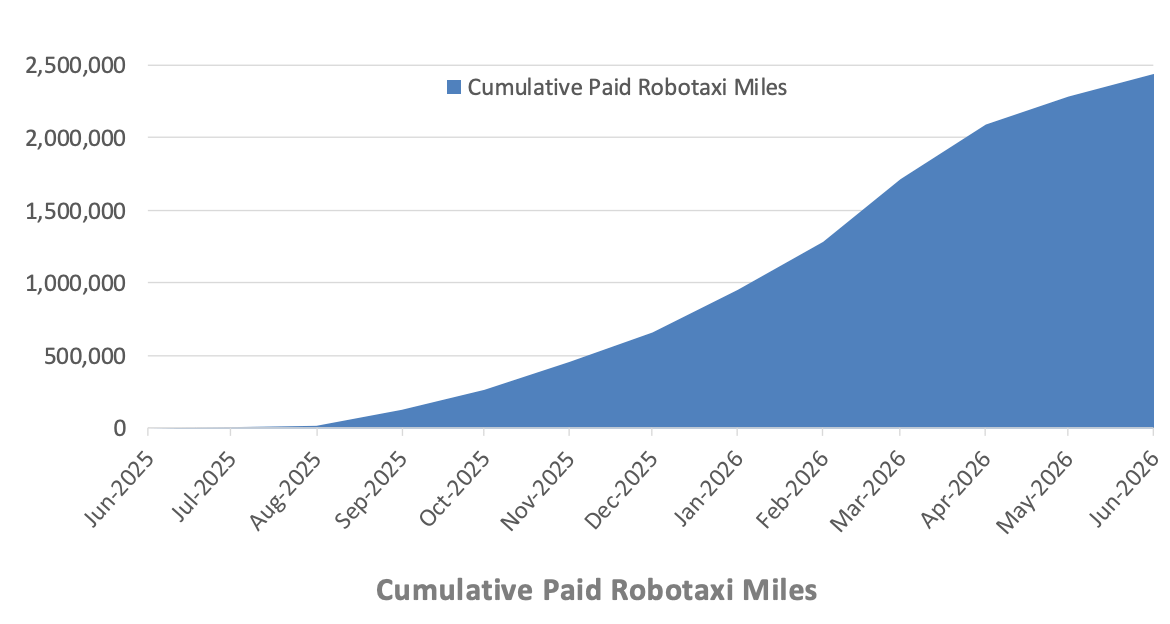
Set that against the chart Tesla published the same day. The chart shows cumulative paid robotaxi miles, which reads as steady growth at a glance. Broken down by quarter, paid miles went from roughly 1.1 million in Q1 to roughly 700,000 in Q2. Down about 36 percent, while the footprint expanded.
Source: Tesla Q2/2026 Earnings Presentation
There are two ways to read this, and I want to give both properly.
Read one way, the metrics are simply measuring different things and both statements are true. Unsupervised miles are a growing subset inside a shrinking paid total. Vehicles that were carrying paying passengers in Q1 may have been reassigned to unsupervised validation, which would depress paid miles precisely because the ramp is being prepared. TechCrunch also notes the paid figure likely includes Bay Area miles driven with a safety driver, which Tesla counts as “Robotaxi coverage,” so the denominator is doing work.
Read another way, a company that expanded from four markets to seven and still moved fewer paying customers has a utilisation problem, not a measurement problem. If the fleet were growing and the vehicles were in near-continuous operation, as management describes, paid miles should rise.
I lean toward the first reading, but I hold it loosely, and I want to be honest about why I cannot do better. Tesla does not disclose fleet size, vehicle utilisation, or intervention rates. It published a cumulative chart rather than a quarterly one, which is a presentation choice that makes the decline harder to see. When a company gives you the metric that grows and withholds the metrics that would explain it, the honest position is that the direction is unclear and the disclosure is the problem.
Then came the admission. Wells Fargo’s Colin Langan asked the obvious question: why is the vehicle count still in the dozens rather than the hundreds, and why not scale one city instead of adding new ones? Elluswamy answered on generality, arguing the stack needs to prove it works across many cities without per-city effort. Taneja added that Tesla wants to “sort these things out in a smaller fleet in a controlled manner” before going “really high in terms of deployment.”
Then Musk said this:
“One of the things for CyberCab that should be noted is because it is a new vehicle chassis, we need to accumulate driving data that is specific to the CyberCab before we can put a lot of them on the road. So unlike, say, Model 3 and Model Y and our other vehicles, where we’ve got a lot of vehicles on the road, millions of vehicles on the road, we don’t have that for CyberCabs. So we actually have to accumulate miles with CyberCabs that are retrofitted with steering wheels and acceleration braking pedals, that kind of thing, to calibrate to the CyberCab chassis.”
Read that again with the last few years in mind.
For years, the central argument for Tesla’s data advantage has been that its roughly ten million customer vehicles are quietly collecting the miles that will train future robotaxis. That fleet was the moat. It was the reason the vision-only bet was supposed to win: nobody else has that much real-world data, and every Tesla sold makes the robotaxi better.
Musk has now said that this is not enough for the vehicle Tesla intends to build its robotaxi fleet around. The Cybercab needs its own miles, collected on retrofitted Cybercabs with steering wheels and pedals bolted back on, because the chassis is different.
I want to be fair about what this does and does not mean. Chassis-specific calibration is normal engineering, not an admission of failure. Every serious AV programme revalidates when the platform changes. Cybercabs run continuously once deployed, so accumulating miles need not take long.
But it narrows the data-moat argument in a way that has not been priced. The claim was never “we have lots of driving data.” It was “our fleet’s data transfers to the product we will scale.” This week Tesla said, on the record, that it does not transfer cleanly across form factors. That is a meaningful qualification, and it came from the company itself.
It also explains the refusal on lidar. If a new chassis resets the data collection to some extent, a new sensor suite presumably resets it too. That is a coherent engineering reason to hold the line on cameras, and it is a better one than the rhetorical version Elluswamy offered in the same call, when he said the “so-called experts” claiming you need lidar, radar and HD maps have been shown wrong. A 380,000-mile record is not yet the basis for that victory lap. Waymo has accumulated roughly 220 million autonomous miles.
Safety is the constraint, and Tesla just said so twice
In CW28 we set out two camps explaining why Tesla’s fleet was not growing. One said the constraint was safety and technical readiness. The other said it was regulation, and read the rollout as gated on federal rulemaking. I declared a lean toward the safety camp, and the reason I gave was specific: because Musk said it himself, and admissions against interest carry more weight than outside inference.
This week the test resolved.
LightShed’s Walt Piecyk asked directly what Tesla still needs from the federal government to unlock the Cybercab ramp. Lars Moravy, SVP of Vehicle Engineering, answered:
“The short answer is no. I mean, I think we have a great relationship with NHTSA and Administrator Morrison, especially. And I think they’re just following through with what the public wants and the world knows is coming.”
That is Tesla saying that Washington is not the gate. Moravy noted friction remains at state level and called New Jersey “a little bit disheartening,” which is consistent with what we covered in CW30 on the S1677 fight. But on the federal question, the answer was no.
And Musk gave the safety framing again in his opening remarks:
“Our goals are very ambitious for Robotaxi, but we do need to be cautious about causing any accidents or causing any harm to anyone. Although there are I think 30 to 40,000 automotive deaths per year in the United States alone, most of those do not generate any press... But if we injure even one person, it will be worldwide headline news. And regulators will immediately clamp down on our activities.”
Two things need saying about that quote, and they point in opposite directions.
The first is that it deserves credit rather than the reflex it usually gets. A CEO saying he does not want to hurt anyone, and slowing his own most valuable programme to avoid it, is a safety culture doing what a safety culture is for. And he is factually right about the asymmetry. This industry has a graveyard that proves it. Uber’s ATG did not survive its deadly incident. Cruise did not survive its pedestrian-dragging incident, and it was the concealment as much as the collision that finished it. Neither company was undone by a pattern of failure. Each was undone by one event. So the caution is not theatre and it is not spin. It is learned behaviour, and the people who read Musk as a cowboy on this specific question are not reading the record.
The second thing is what that caution reveals. A system you trust does not need to be rationed. Waymo runs roughly 3,800 vehicles and does not throttle expansion out of fear of a single incident, it throttles on operations, depots, permits and staffing. Tesla is running dozens. If the stack were as generalised as “it works anywhere” has implied for years, the brake would not need to be held down this hard.
And that is where this connects to the Cybercab admission, because the two are not separate observations. They interlock. Tesla is probably being this cautious precisely because it does not yet have the data to be confident in the vehicle it intends to scale. The caution is not sitting alongside the data gate. It is the symptom of it. Read that way, this week is a maturity signal rather than a statement of philosophy: cautious on the Cybercab because early on the Cybercab.
So the CW28 lean was right, and I am going to sharpen it rather than repeat it. The constraint is not regulation. It is also not safety in the general sense. It is something more specific and more tractable: the vehicle Tesla plans to scale on does not yet have data of its own. That reframes the whole question. A safety constraint is open-ended and worrying. A data-accumulation constraint on a vehicle already in production is a schedule problem, and schedule problems get solved.
That is the most constructive reading available of this week, and it is the one I hold. But I want to be honest about how much it concedes. A schedule problem still has to have a schedule, and the severity of the caution tells you this one has not really started. Tesla is not throttling a proven system while it clears paperwork. It is throttling because the confidence is not there yet, on the vehicle that matters most.
There is also a caveat delivered by Tesla’s own history: mileage thresholds have been a poor predictor here. Musk set 10 billion FSD miles as the bar for safe unsupervised driving in January, up from a prior 6 billion, and Tesla passed it in May with no visible change in Austin. Any specific Cybercab-mile figure should be held loosely.
Three cars, one tree stump
While the call was making the case for a safety-first culture, NHTSA data was filling in what that looks like operationally.
Electrek reported that Tesla filed four new Robotaxi crash reports, and one of them is genuinely revealing. Report 13781-15395, from May in Houston: a Model Y was stopped on a dead-end residential road and needed help getting out. In Tesla’s own words, “while the ADS was being supported remotely out of the dead end road, the vehicle entered a grassy slope. As the remote assistance operator continued to recover the vehicle, they made contact with a hidden tree stump.”
The damage was trivial. Property damage only, no injuries, pre-crash speed of 2 mph. The significance is not the impact.
It is the third crash Tesla has reported in which a human operating the car remotely caused the collision, and the first coded in the structured data field as “Remote (Commercial / Test)” across its 22 unique ADS incident reports. The two earlier cases have an identical shape: the system got stuck, a teleoperator took over, the teleoperator hit something. A metal fence at 8 mph in July 2025. A construction barricade at 9 mph in January 2026.
Now the density. Per Robotaxi Tracker data cited by Electrek, Tesla has had roughly three active vehicles in Houston. Three. About a month after launch, one had to be rescued from a dead-end street, and the rescue ended in a collision.
Starlink, Semi, and the question nobody answered
Two other items from the call are worth logging, and neither is worth over-reading.
The first is Starlink, and Musk’s case for putting it in the vehicle is more interesting than the in-car entertainment framing suggests. A robotaxi cannot afford connectivity dead zones, because a car that loses its link mid-route is a car somebody has to go and collect. As he put it, you cannot have “robo-taxis getting stuck in these like Bermuda Triangles” of absent cellular coverage. That makes Starlink a fleet-reliability decision rather than a passenger feature, and Tesla intends to extend it from Cybercab to every vehicle in markets where Starlink is active. Convert it into economics and it is a recovery-cost argument: fewer stranded vehicles, fewer field interventions, less of the manual labour that sits underneath every robotaxi unit-economics model.
On the merger, Colin Langan asked whether Musk sees synergies from combining SpaceX and Tesla. The answer was a non-answer, “obviously, we can’t talk about combining companies,” handed straight to general counsel Brandon Ehrhart. In CW30 we noted that with a SpaceX acquisition partly priced in, the incentive to talk the stock up inverts, and an unusually downbeat Musk would be the tell. He was subdued, and unwell by his own account. I am not building an argument on that. What is observable is that the engineering entanglement keeps deepening: Grok in the car and driving Digital Optimus, Starlink in Cybercab and eventually the whole fleet, SpaceX buying Megapacks, TeraFab described as a joint project. These companies are converging in engineering whether or not they converge on a cap table.
One roadmap item will matter more than it looks. Asked about Semi autonomy, Musk put self-driving on the truck at “around the end of this year or early next year,” explicitly deprioritised behind Model 3, Model Y and Cybercab for six months.
And no, the robotaxis are not going on Uber
Bank of America’s Alex asked whether Tesla would consider third-party distribution through rideshare providers to raise utilisation. Musk was unequivocal:
“We expect to be vertically integrated with Robotaxi as we are in the rest of our business. So I don’t think we’re going to have any demand challenges with Robotaxi. The economics will be so compelling that I think we will really have a lot more desire to use the service. I think demand will outstrip our ability to service the demand.”
Tesla has now closed that door twice in public, which makes the timing of the next story almost too neat.
Waymo puts a date on the divorce
In CW28 we covered the end of the Waymo-Uber partnership in Phoenix and called it the first market where Uber’s value to an AV developer hit zero. The thesis line was that Uber’s value peaks on day one and decays with every ride, and we refined the platform position to “a bridge, not a moat.” We said the same math was waiting in Austin and Atlanta, where the fleets are far larger and the arrangement exclusive. We explicitly declined to guess when.
This week the timetable arrived. The Financial Times reported that Waymo is looking for a way out of the Uber deal covering Austin and Atlanta. Uber confirmed to TechCrunch that Waymo has told it it intends to offer robotaxis on its own app in both markets starting in January 2028, alongside the existing Uber offering, and that the contract covering the two cities ends in May 2028.
Note the structure. Waymo is not exiting Uber in January 2028. It is going parallel, running its own app alongside Uber’s until the contract expires in May. That is a developer with the capital, brand and operating muscle to build its own demand layer choosing to test it against the platform before walking. The bridge is being crossed slowly and in full view.
This also sharpens the read on Uber’s lobbying. Uber is pushing for hybrid-network mandates in D.C. and, via circulated language in New Jersey, an 85 percent human-driver floor that would bar Waymo, Zoox and Tesla from their own apps. Phoenix told us Uber’s position decays as developers scale. The lobbying told us Uber knows it. A confirmed 2028 exit date in its two largest AV markets tells you why the lobbying has the urgency it does.
Motional bets the company on a different architecture
One more, and it belongs in this story rather than beside it.
Motional is targeting driverless commercial operations on the Uber network in Las Vegas by year end, and it has rebuilt its stack around what it calls Large Driving Models. President and CEO Laura Major, who took the role in 2025 after five years as CTO, described the pivot as requiring near-term sacrifices for a stronger long-term foundation. Alongside the LDMs sits a Continuous Learning Framework designed to ingest daily fleet data, mine edge cases and retrain models concurrently. The vehicle is the Ioniq 5 robotaxi, designed for ride-hailing from the outset and manufactured at Hyundai Motor Group’s Innovation Center in Singapore.
Read past the terminology and this is a specific bet in a debate we have tracked for years: that end-to-end learned driving generalises across cities better than stacks tuned city by city. Same wager Wayve is making with Uber and Stellantis, Tesla, and Momenta with its R7 world model, and the one Waymo has hedged rather than taken outright.
It matters commercially because of expansion cost. If learned models genuinely generalise, the time and capital to enter a new market compress, and the problem that has killed more AV programmes than any technical failure becomes tractable. If they do not, Motional has spent its rebuilding years on an architecture and still owes the per-city work.
Las Vegas by year end is the test, and it is a fair one. Note also what Motional is not doing: it is launching on Uber’s network, not its own app. In a week where Waymo put a date on leaving Uber, Motional is arriving. The bridge decays for developers who can afford to cross it. For everyone else it stays essential, which is exactly the refinement we made in CW30.
What this means and what to watch
First, the disclosure is now the story. Tesla published a cumulative chart that obscures a 36 percent quarterly decline in paid robotaxi miles, and does not disclose fleet size, utilisation or intervention rates. I lean toward the benign explanation, that vehicles moved into unsupervised calibration. I cannot verify it, and neither can you. Until Tesla publishes quarterly paid miles and an active vehicle count, every claim about exponential growth is unfalsifiable. The company that unredacted its crash narratives knows the value of transparency. It should apply the same standard here.
Second, the constraint is now specific, and that is good news for Tesla. Washington is not the gate, by Tesla’s own answer. The gate is Cybercab-specific driving data on a vehicle already in production, accumulated on retrofitted units. That is a schedule problem, not an open-ended one.
Third, the data moat needs to be restated, not retired. “Ten million Teslas are training the robotaxi” was never quite the claim it sounded like, and Tesla has now qualified it in public. The fleet advantage is real for FSD on Model 3 and Model Y, where 1.5 million paying customers is a genuinely strong position. It is weaker than advertised for the purpose-built vehicle the valuation depends on.
Fourth, watch the capex-versus-evidence gap through year end. At least $16.7 billion of spending remains in the second half against a robotaxi business that moved 700,000 paid miles last quarter. Tesla has $43.5 billion and access to $30 billion more in debt, so this is not a solvency question. It is a patience question, and this week the market showed exactly how much patience it has left.
🔗 TechCrunch / TechCrunch (2) / TechCrunch (3) / TechCrunch (4) / Electrek / App Economy Insights / Reuters / Reuters (2) / LightShed / Automotive World / Autonomy Signals
Enjoying the AV Market Strategist?
If you find value in these deep-dives and enjoy the updates on autonomy each week — you can support my work.
Your contribution helps me access better data sources, industry reports, and research tools to keep every issue sharper and more insightful.
The newsletter will always remain free to read, whether you choose to support or not — but every bit of backing helps me make it even better.
CHINA CORNER: One Outage Froze a National Market for Three Months. This Week It Restarted.
One failure in Wuhan stopped robotaxi licensing across China in April. One regulator-run review restarted it in July.
The licences come back on
China has started issuing robotaxi licences again, according to a Bloomberg report, after suspending new permits in April.
Regular readers know exactly why they stopped. On the night of March 31, a number of Baidu Apollo Go robotaxis stalled on roads in Wuhan, stranding passengers on a busy elevated road. Wuhan traffic police found a system malfunction. We covered it at the time, and the consequence was an industry-wide safety review and a freeze on new permits that hundreds of Baidu vehicles in Wuhan sat out.
The review completed in late June, and licence issuance is now resuming gradually, city by city. Local residents have posted videos since early July showing Apollo Go vehicles back on Wuhan streets, some with safety drivers aboard.
Notice what that sequence establishes. A single operational failure froze an entire national market for roughly three months, and the industry came back only after a regulator-run review. Chinese AV regulation is often described as permissive. It is better described as fast in both directions.
The first new permit goes to Momenta, in the city rewriting its own rules
One of the first permits went to Momenta, for road testing in Shenzhen.
Shenzhen matters more than the permit does. The city recently amended its intelligent connected vehicle regulation, establishing a tiered road management system, lowering barriers to entry, and explicitly exploring opening the entire city to robotaxis rather than the district-by-district approach used almost everywhere else. If a city of 17 million opens wholesale, the operating question stops being which streets you are allowed on.
That is the part worth internalising. In China, access is something a city can decide to grant at scale, and cities compete to grant it. Shenzhen is not responding to Momenta. It is bidding for the industry.
For Momenta, Shenzhen becomes its fourth core Chinese city after Shanghai, Suzhou and Wuxi, on top of an international footprint that includes Munich and Abu Dhabi. Its testing platform is powered by the R7 world model launched in April, trained on data from over 12 billion kilometres of mass-produced driving. That is the L2-to-L4 flywheel we have documented repeatedly: ship advanced driver assistance at production scale, use the resulting data to build the driverless system.
Momenta listed in Hong Kong on 8 July, raising about HK$6.8 billion, which we broke down in CW27. It said then it would put roughly 60 percent of proceeds into R&D and 20 percent into commercialising robotaxis.
Staying with Momenta: the robovan move
According to 21jingji, Momenta has entered the robovan market, with vehicles operating in its home city of Suzhou for several months.
The strategic logic is cost allocation. Momenta’s stated ambition is a physical AI foundation platform supporting passenger vehicles, robovans, robotrucks and robotaxis from one base, with robotics as a possible extension. Entering autonomous freight spreads a very high fixed R&D cost across more revenue lines. WeRide has run the same play with its mass-produced W5 robovan, deployed in 2025, alongside robosweepers and robobuses.
The market they are entering is large and already spoken for. The China Federation of Logistics and Purchasing projects annual production and sales reaching 860,000 units by 2030, with a total fleet above two million.
But as we sized it in CW26, this is effectively a duopoly. As of Q1 2026, Zelos had more than 25,000 robovans for a 52.3 percent share, and Neolix had 17,000 for 36.2 percent. Together with Rino, the top three control more than 95 percent of the market. Last week we logged CaoCao, Geely’s ride-hailing arm, entering the same market. Momenta makes it two new entrants against that structure in two weeks.
The reason the duopoly is now attackable is cost. LiDAR has fallen from around 100,000 yuan, roughly $14,700, in the early stages to the 1,000-yuan range. The bill of materials for an autonomous delivery vehicle has generally dropped below 100,000 yuan. When hardware costs collapse by two orders of magnitude, incumbency built on being early stops protecting anyone.
The binding constraint on robovans is neither technology nor cost. It is that China has no national product approval or certification system for autonomous delivery vehicles at all. Local governments set their own rules, so every new city means a fresh permit application. A market heading for two million vehicles is being built one municipal approval at a time, which is the same fragmentation American operators complain about.
Pony.ai rents a national service network
Permission gets you onto the road. It does not keep you there, which is what this next deal is about.
Pony.ai signed an agreement with JD Auto Service, JD.com’s automotive maintenance arm, to build a standardised maintenance and spare-parts network for its Chinese robotaxi fleet. It covers Beijing, Shanghai, Guangzhou and Shenzhen initially, against a target of more than 3,500 vehicles across more than 20 cities by the end of 2026.
The mechanics are the point. JD Auto Service connects its existing service network to Pony’s fleet management platform to coordinate maintenance capacity and parts supply, and the two integrate systems for work-order dispatch, service tracking and settlement, automating from fault detection through to completion. A vehicle flags a fault, the system finds capacity, dispatches the work order, tracks it and settles it, without a human coordinating between two companies.
Founder and CEO Dr. James Peng framed it as we would: robotaxi commercialisation is as much an operational challenge as a technological one, with vehicle availability, service consistency and lifecycle costs becoming critical unit-economics drivers as fleets scale.
Convert that into economics. Pony has already reached unit-economics breakeven in Guangzhou and Shenzhen on its seventh-generation platform. Breakeven at that stage is fragile, and the two variables that break it are vehicle downtime and per-city fixed costs. By renting an existing national service footprint instead of building depots in twenty cities, Pony converts a capital cost into a variable one and protects the margin it just achieved. For a company scaling from hundreds to thousands of vehicles, that is the difference between growth that improves economics and growth that destroys them.
SAIC designs a robotaxi around fleet economics
SAIC Mobility has launched a project to develop a purpose-built, production-ready robotaxi for parent SAIC Motor, debuting in 2027. Announced at a forum during the World Artificial Intelligence Conference in Shanghai, it moves SAIC beyond adapting existing passenger models toward a vehicle designed from the outset for commercial autonomous ride-hailing.
The design brief is the notable part. SAIC Mobility leads product definition using both passenger experience and fleet economics as priorities. Cabin layout and onboard functions are tailored to driverless ride-hailing, and the engineering explicitly aims to simplify fleet management, maintenance and servicing.
The work is split three ways: SAIC Motor handles vehicle engineering and manufacturing, an unnamed autonomous-driving supplier provides the driving system, and SAIC Mobility defines the product and operates the fleet. The supplier has not been identified, though IM Motors representatives joined the launch, and SAIC Mobility has been running a Level 4 fleet in Shanghai’s Pudong district with Momenta since May 2025.
SAIC Mobility brings a real operating record to the design: more than 350,000 passenger orders and over four million kilometres of operation since 2021. That record informs cabin use, vehicle durability, maintenance requirements and fleet efficiency.
Here is the shift this represents. Operators used to evaluate robotaxis on autonomous-driving performance. SAIC is designing one around utilisation and total cost of ownership. That is what a market looks like when the driving is considered close enough to solved that the money moves elsewhere.
And note what SAIC itself concedes about the timetable: commercial deployment depends not only on whether the vehicle is ready, but on permits governing fully driverless passenger services.
Hong Kong takes the driver out
Hong Kong’s Transport Department has authorised testing of fully autonomous passenger vehicles at Chek Lap Kok airport, removing the requirement for a human operator behind the wheel. Remote monitoring stays in place.
Earlier airport trials required a human driver inside each vehicle plus a second operator supervising remotely. Commissioner for Transport Winnie Tse Wing-yee said those tests had been “ideal, safe and operating smoothly.” Only then was the onboard human removed. The conditions attached are substantial: monthly reports, on-site inspections, review of the remote control centres, safety and contingency plans covering vehicle, road and cybersecurity risks, third-party insurance, an electronic data recorder in every vehicle, and labels identifying test vehicles to other road users.
Tse made two points. Asked whether legislative change was required for Level 4 operation without onboard attendants, she said Hong Kong’s existing legal framework is already strong enough, and flexible enough, to regulate this phase. And she pushed back on mileage as a qualifier: hitting a prescribed testing distance would not automatically qualify a project, because the department requires comprehensive data and consistent safety performance.
The operator is Baidu, which took Hong Kong’s first AV pilot licence in November 2024 and has since extended from Chek Lap Kok into North Lantau, Kowloon East and the Southern district, with more vehicles, higher speed limits and designated passenger runs. Apollo Go had covered more than 240,000 kilometres in Hong Kong by the end of May.
Now the ADAS-adjacent news, which is not only about ADAS
Volkswagen will deepen its partnership with Horizon Robotics through their joint venture Carizon, with deliveries of L3-capable vehicles in China beginning as early as the second half of 2027.
The structure matters. Carizon is a joint venture between Cariad, Volkswagen’s software subsidiary, and Horizon Robotics, established in Beijing in December 2023, with Volkswagen holding 60 percent on roughly €2.4 billion invested. Under a white-box licensing model, Carizon gets access to Horizon’s AI foundation model to build Volkswagen’s own unified driving solution, working with Horizon’s C7H system-on-chip, still under development, and its GAIA world-model data platform. Stated scope covers L3, where the driver can take their eyes off the road, and L4 for robotaxis, integrated with Volkswagen’s China Electronic Architecture.
Nearer term, Carizon’s full-scenario assistance solution has entered mass production with urban navigation-assisted driving, rolling out across seven new electrified models from Volkswagen’s three Chinese joint ventures this quarter.
Robotaxis are a future business for the OEMs. Advanced assisted driving is a present one. More than 30 percent of new vehicles sold in China in the first half of this year came with advanced navigation-assisted driving, according to MIIT. In that market, this capability is not a premium option. It is table stakes, and Volkswagen cannot ship without it.
Which is why international OEMs keep buying Chinese autonomy. Volkswagen has Horizon Robotics for the driving stack and Xpeng for the electronics platform, with the jointly developed ID. UNYX 08 on sale in China since April. Volkswagen CEO Oliver Blume framed the Horizon deal as reinforcing competitiveness in China and opening “new opportunities in selected international markets,” which is the quiet part: technology developed in China, exported outward.
And Volkswagen’s other Chinese partner has export plans of its own
Staying with Volkswagen’s partnerships, Xpeng has confirmed it will bring VLA 2.0, its next-generation intelligent driving system, to Australia by the end of 2027, pending regulatory approval. Australia is among the first right-hand-drive markets slated to receive it as part of a 2027 global launch.
Be precise about what this is. VLA 2.0 powers Xpeng’s NGP system, which follows navigation directions, takes turns and responds to hazards, and it is being positioned as the first credible rival to Tesla’s FSD Supervised. Like FSD, it is Level 2. The driver must watch the road at all times and remains legally in control in a collision, with the expectation of taking over to avoid one. Hands off the wheel, eyes on the road, liability unchanged.
Xpeng vice president Dr. Brian Gu said Xpeng is looking for partners to trial robotaxis in Australia on VLA 2.0 once the federal government permits operation without human supervision.
VLA 2.0 can be sold in Australia in 2027 because a supervised L2 system requires almost nothing from a regulator: the human remains liable, so the state carries no new risk. The robotaxi version cannot ship until Canberra allows operation without human supervision, which is why Gu is looking for trial partners rather than announcing a launch. Same company, same software, two completely different waiting rooms.
That is the export machine running on both tracks at once, and it is not an accident that the track requiring no permission is the one with a date on it.
What this means and what to watch
First, the freeze is the risk nobody outside China prices. A single operational failure in one city stopped licensing nationwide for roughly three months, and hundreds of vehicles sat idle waiting for a review they could not influence. Chinese AV regulation is usually described as permissive. Fast in both directions is the better description, and the second direction is the one that should appear in any valuation of a Chinese operator. Watch whether the returning fleets scale faster than they did before the freeze.
Second, permission is becoming something cities compete to give. Shenzhen amended its rules, lowered barriers and is exploring opening the entire city, and the first new permit of the post-freeze era landed there. That is a municipality using regulatory access as industrial policy. Over the next months the meaningful gap between Chinese cities will not be traffic complexity or population, it will be how much of the city a regulator is willing to open at once. Track the ODD sizes, not the launch announcements.
Third, the robovan market is being built one municipal approval at a time. No national product approval or certification system exists, so every city is a separate application. That is what protects Zelos at 52.3 percent and Neolix at 36.2 percent far more than their technology does, because permits accumulate to whoever has been applying longest. The thing that would break the duopoly fastest is not a better robovan. It is Beijing writing a national certification standard, and I would watch for that harder than for any product launch.
🔗 CnEVPost / CnEVPost (2) / CnEVPost (3) / Gasgoo / Gasgoo (2) / Automotive World / tech360 / Reuters / Drive.com
💡 Quick Takes
Aurora launched second-generation driverless trucks
Built on the International LT Series with hardware rated for one million miles, running ten Sun Belt routes, Safety Case closed before launch. Roush is upfitting toward a 1,000-truck annual run rate later this year.
🔗 Business Wire
Kazakhstan will build autonomous SITRAK heavy trucks by 2028
Announced 21 July by Industry Minister Yersayin Nagaspayev, out of President Tokayev’s China visit, bundled with Li Auto, Omoda and Jaecoo production and a BYD charging network. SITRAK is Sinotruk’s premium brand, developed with Germany’s MAN. No site or capacity disclosed. The context that makes it more than an assembly deal: Kazakhstan and Russia opened a pilot cross-border driverless freight corridor in May, and Baidu’s Apollo Go entered Kazakhstan earlier this year. Chinese stacks, local assembly, Eurasian corridors.
🔗 The Times of Central Asia
Aidoptation won the EU’s first L4 highway testing permit
100 km of the E313 and E314 in Belgian Limburg at speeds up to 120 km/h, approved by federal and Flemish authorities. Its EdgeDrive platform uses deterministic first-principles models with no AI in the decision loop, specifically so results stay traceable and auditable for regulators and insurers. Safety driver aboard, Ethias insuring.
🔗 Business Wire
Einride bought charging software startup Flipturn for $38 million in stock
Its first acquisition since June’s Nasdaq debut. Flipturn’s platform talks to any charger over OCPP and integrates on-site solar and storage.
🔗 TechCrunch
Mobileye’s Amnon Shashua is stepping aside after nearly three decades
He will remain in post until a replacement is hired, according to a regulatory filing on Thursday. Under Shashua it also moved past selling chips to automakers and started building the systems that do the driving, now supplied to Volkswagen and its MOIA subsidiary. In January it bought Shashua’s own humanoid robotics startup, Mentee Robotics, for $900 million, which he called part of “Mobileye 3.0,” a phase centred on robotics and automotive AI. In June it said it would go further and launch its own robotaxi service in a US city in 2027, which we covered in CW26. He is handing over as the company stops being purely a supplier and starts competing with the customers it sells to.
🔗 TechCrunch
Travis Kalanick’s Atoms raised $1.7 billion led by a16z, with Uber participating
Ben Horowitz joins the board. Atoms sits atop CloudKitchens and acquired Anthony Levandowski’s Pronto in March; Kalanick wants to build a “wheelbase for robots” and move into mining. The detail for this readership is Uber writing a cheque to its ousted founder.
🔗 TechCrunch
China’s CiDi is taking autonomous mining equipment overseas
Revenue more than doubled last year to 884.8 million yuan, roughly $130.6 million, on a fleet above 1,700 vehicles across 30 quarries and mines, with about 10 percent of Chinese mining trucks now driverless. One operator monitors around 100 trucks remotely, which is what a mapped private-road ODD buys you. Overseas revenue should reach a double-digit share next year, with robotic explosive-hauling units due this quarter.
🔗 Reuters
MINIEYE and StarCharge are building automated charging hubs for driverless fleets
L4 driving and dispatch plus charging equipment and site operations, aimed at an end-to-end loop for MINIEYE’s Bamboo Robovan: assignment, autonomous parking, charging, inspection and maintenance with nobody on site. It follows a DiDi Delivery deal on 13 July covering freight demand. Same conclusion Pony reached with JD this week, arriving from the delivery side.
🔗 Gasgoo
Japan’s T2 raised ¥5 billion, about $31 million, in a Series B
Total funding now past $101 million since 2020. More than 50 transport companies use its in-house L2 system, and an L4 trunk-route product is targeted for commercial introduction in 2027. The same driver-shortage logic pulling autonomy into US trucking, in a country where the demographics are more severe.
🔗 Yahoo Finance
Applied Intuition launched Dana, an agentic platform for physical AI
Building, testing, deploying and operating physical AI across software-defined vehicles, ADAS, mining, construction and robotics, with the evaluation and traceability safety-critical work requires. Used internally for a year across automotive, trucking, mining and agriculture customers.
🔗 International Mining
🎧 Autonomy Insiders
Certification, type approval, homologation. Not the sexiest words in autonomous driving, but arguably the most decisive ones for whether AVs ever reach European roads at scale.
The EU’s Level 4 regulation (2022/1426) has existed for four years. As of today, not a single vehicle holds EU type approval under it. The common narrative blames slow regulation. My guest tells a different story: the framework is ready, the technical services are ready, and the real bottleneck sits inside the companies themselves.
Dirk Fratzke is Project Leader in the Autonomous Driving & ADAS department at TÜV SÜD, the independent testing organization that assesses AV companies across three continents.
📚 Worth Reading/Listening
Harry Campbell: Waymo’s Lead Is Real. Its Biggest Test Is What Comes Next
📊 Weekly Performance
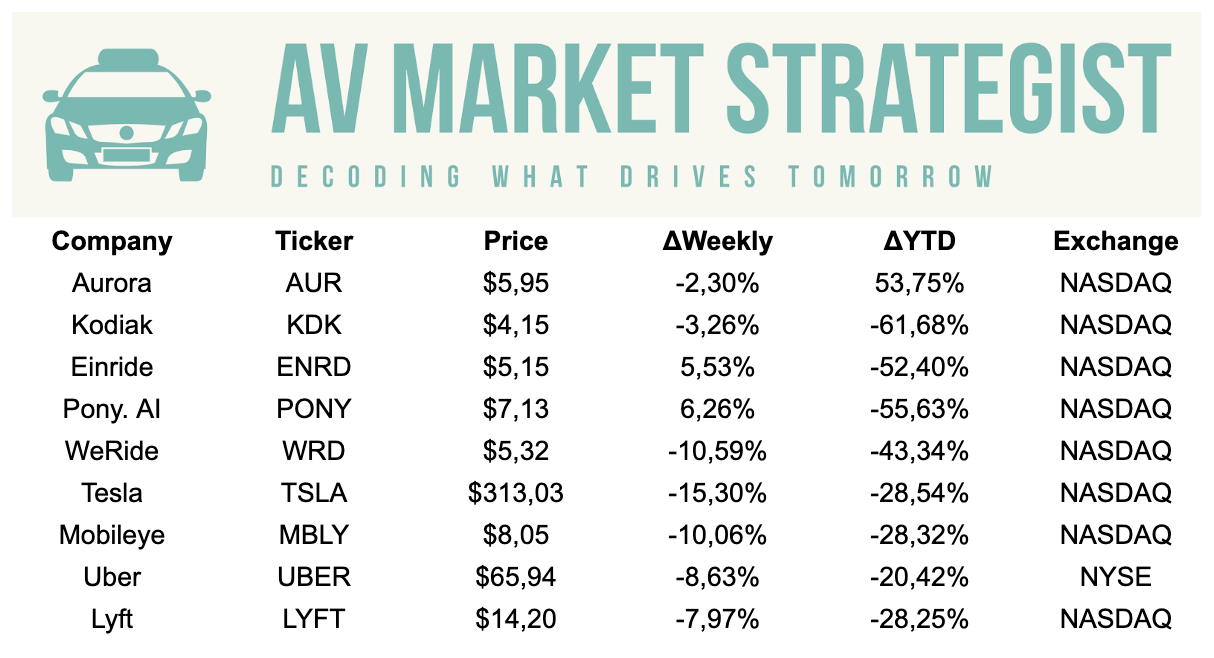
Note: Stock performance data as of July 26th, 2026. Past performance does not indicate future returns.
Thanks for reading!
If you found value in this newsletter, please consider sharing it with a friend or colleague who might benefit from these insights.
And if you haven’t already, subscribe to stay updated on the latest developments in the autonomous driving industry.
Disclaimer: This newsletter is provided for general informational and educational purposes only and is subject to change without notice. While we obtain information from sources we believe to be reliable, we do not guarantee its accuracy, completeness, or timeliness. We accept no responsibility for any actions taken based on this newsletter or for any losses resulting from its use. Nothing in this newsletter constitutes, or is intended to constitute, financial, investment, trading, legal, accounting, or tax advice. The content does not take into account your individual objectives, financial situation, or needs and must not be relied upon as personalized recommendations to buy, sell, or hold any security or other financial instrument. You should always do your own research and consult a licensed financial professional before making any investment decisions. Any opinions or views expressed in this newsletter are those of the authors at the time of publication and may change without notice. They do not necessarily reflect the opinions of any affiliated entities.
Really smart way for Waymo to leave Uber! They can work out all the kinks in their app and support processes without giving up all their revenue from Uber. Thanks again for an awesome update, Daniel!