

👋 Hey everyone,
This edition breaks down Waymo’s freeway expansion and why vehicle supply—not technology—is now the defining constraint. We’ll analyze the autonomous trucking SPAC wave and take a look at Kodiak’s first earnings.
Plus: regulatory wins from Vietnam to Germany, South Korea’s ambitious 2028 timeline, and why Abu Dhabi is becoming a crucial testing ground outside China and the U.S.
⏱️ ~3,700 words, 17 minute read
🚗 Waymo’s Freeway Unlock
When Google’s self-driving car project first rolled out in 2009, engineers actually started on highways, specifically Interstate 280 running through Silicon Valley. More than fifteen years later, those same roads are finally seeing driverless vehicles return, but this time without safety drivers behind the wheel.
This week, Waymo announced that its robotaxi service now operates on freeways across the San Francisco Bay Area, Los Angeles, and Phoenix. The expansion represents both a technical achievement and a strategic inflection point: for the first time, Waymo can stitch together entire metropolitan regions rather than operating in isolated urban pockets. The Bay Area service area now spans 260 square miles, and riders can book trips that include segments on US-101, I-280, I-380, and other major corridors. In Phoenix, coverage includes US-60, I-10, I-17, and Loop 202. Los Angeles riders gain access to I-5, I-10, I-405, and multiple state routes.
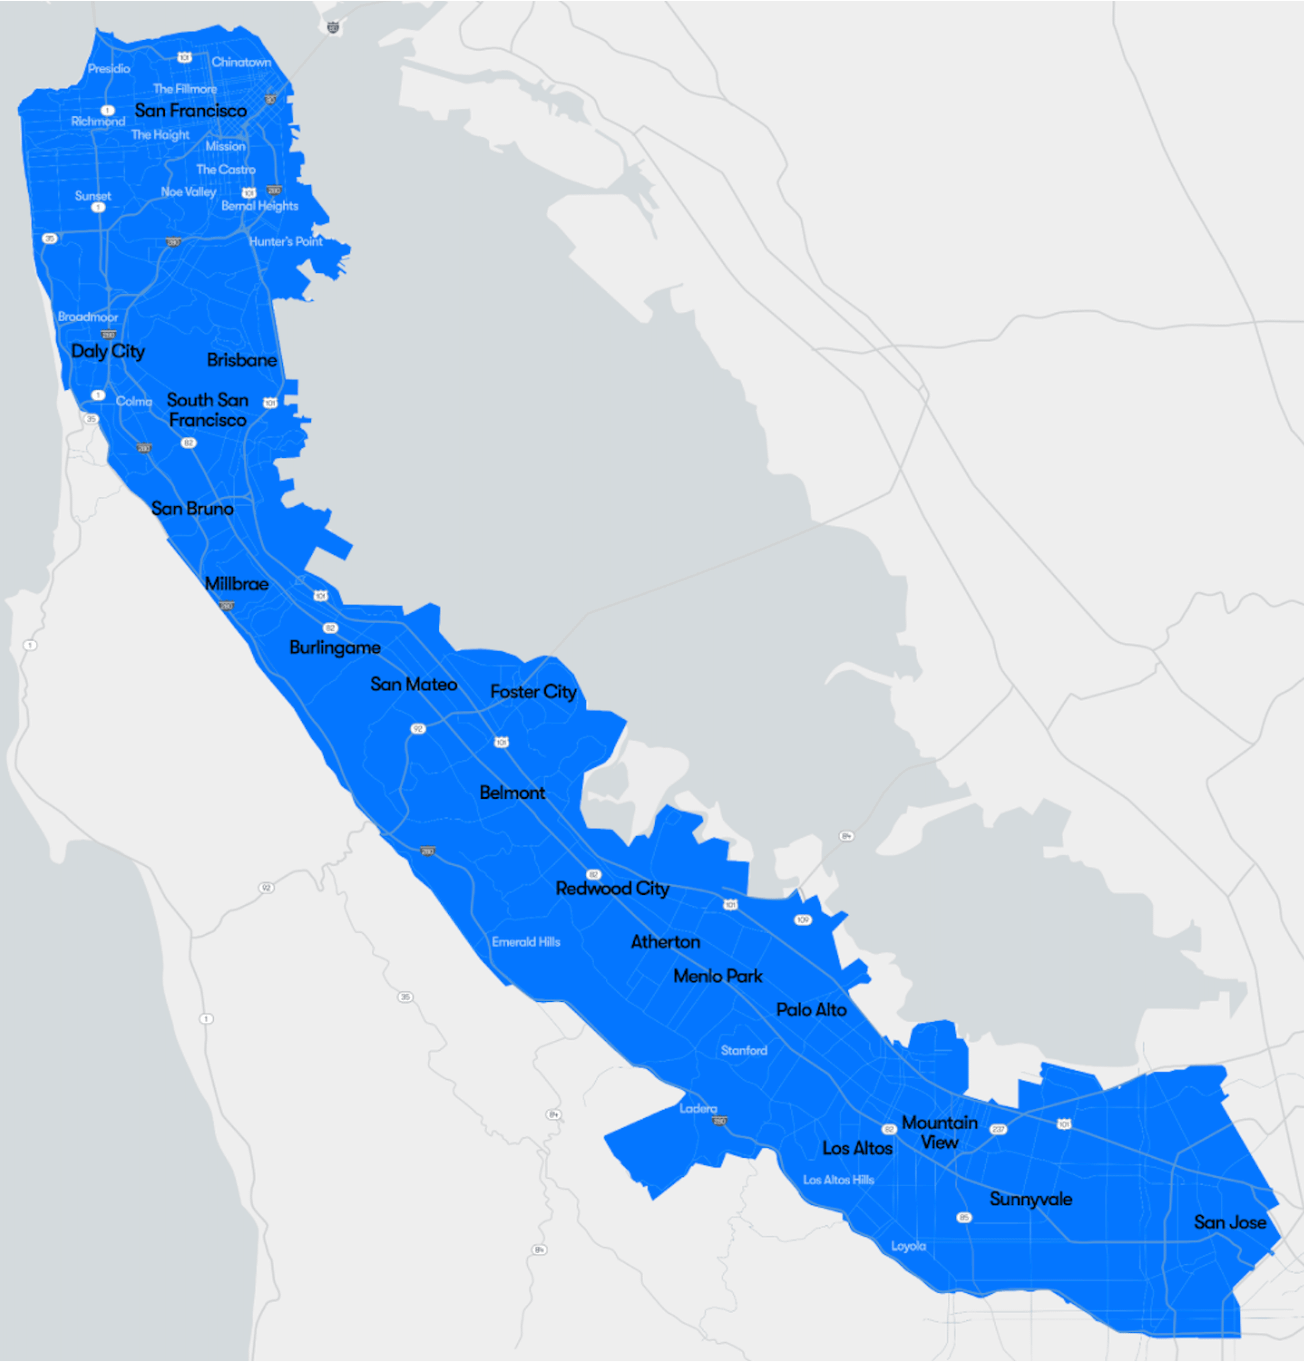
Source: Waymo
Why Freeways Matter—And Why They Took So Long
Freeway driving is often described as technically simpler than navigating city streets. There are no pedestrians, no traffic lights, no cross-traffic or sudden left turns from oncoming lanes. Lane markings are clearer, behavior is more predictable, and the decision space is constrained. It’s precisely why early autonomous vehicle projects, from adaptive cruise control to Tesla’s Autopilot to Mercedes Drive Pilot, focused on highways first.
But simplicity in one dimension creates complexity in another. At 70 mph braking distances extend dramatically, reaction windows shrink. A fender-bender on a residential street becomes a potentially fatal collision on a freeway. The physics don’t negotiate.
Waymo co-CEO Dmitri Dolgov acknowledged this trade-off explicitly: “Freeway driving is one of those things that’s very easy to learn, but very hard to master.” While the operational environment is simpler, the stakes are exponentially higher. Waymo’s engineering team faced a particular challenge: safety-critical events on highways are rare by definition, which meant they couldn’t accumulate enough real-world edge cases to train the system through observation alone.
To solve this, Waymo supplemented on-road testing with closed-course scenarios and simulation-generated data. The company built redundancies into the vehicle architecture, dual onboard computers provide backup if one fails, and trained the system to exit the freeway entirely in emergencies rather than simply pulling onto the shoulder, where hundreds of Americans are killed annually in secondary incidents.
Waymo has been testing employee-only freeway rides for over a year. The extended timeline suggests the company wanted to demonstrate overwhelming safety performance before exposing public riders to higher-speed environments where perception of risk and media scrutiny intensifies.
What This Unlocks Operationally
The immediate benefit is dramatic: Waymo estimates freeway-enabled routes can cut travel times in half. A trip from San Francisco to Mountain View that previously required winding through surface streets now zips down US-101. For riders, this transforms the service from a curiosity into a viable alternative for commutes, airport runs, and regional travel.
For Waymo’s business model, shorter trip times mean higher vehicle utilization. A robotaxi that completes two trips per hour instead of one generates double the revenue without doubling the capital deployed. This operational leverage is critical as the company scales. Every incremental efficiency gain compounds across the fleet.
The airport angle is particularly strategic. Ride-hailing data consistently shows that airport trips are among the most profitable routes: they’re predictable, high-frequency, and command premium pricing. Waymo now offers curbside pickup at San Jose International Airport, with plans to expand to San Francisco International once testing concludes. In Phoenix, Sky Harbor Airport access is already live. These aren’t just convenience features, they’re essential pieces of infrastructure for competing with Uber and Lyft on the routes that matter most financially.
From a market positioning standpoint, freeway capability removes the last structural constraint that differentiated robotaxis from traditional ride-hailing. Until now, Waymo was excellent for local trips but fundamentally limited for the high-value, high-frequency travel patterns that define metropolitan mobility. That limitation is now gone.
The Safety Calculus and Public Perception Risk
Waymo’s safety record on city streets has been exceptional. The company’s vehicles have logged over 100 million miles, with crash rates and injury rates significantly below human driver benchmarks on the same roads. But freeways introduce a new risk profile, and Waymo executives know the first serious incident will test public tolerance in ways city-street fender-benders have not.
Consider the asymmetry of perception: Waymo could operate flawlessly for years, but a single high-speed crash, even one where the robotaxi isn’t at fault, will generate intense scrutiny. We’ve already seen this dynamic play out.
The emotional volatility is real. A Waymo recently struck and killed a cat in San Francisco, prompting calls to ban the service and even a non-binding city resolution.
Statistically, human drivers would have killed far more cats across the same mileage, but statistics don’t drive headlines or city council meetings. If a single cat can trigger that reaction, imagine the firestorm when the first freeway fatality occurs, regardless of fault attribution.
Waymo co-CEO Tekedra Mawakana acknowledged this openly: no vehicle will be perfect, crashes will eventually happen, but society will accept them if the overall safety record remains superior.
That’s almost certainly correct in the long run, but the transition period, when individual incidents dominate discourse before the statistical benefits become undeniable, will be turbulent.
Fleet Size: The Constraint That Matters Most
Here’s where the story gets more complicated. Bloomberg reported this week that Waymo’s fleet consists of approximately 1,000 vehicles in the Bay Area, 700 in Los Angeles, 500 in Phoenix, 200 in Austin, and 100 in Atlanta. That’s roughly 2,500 vehicles total.
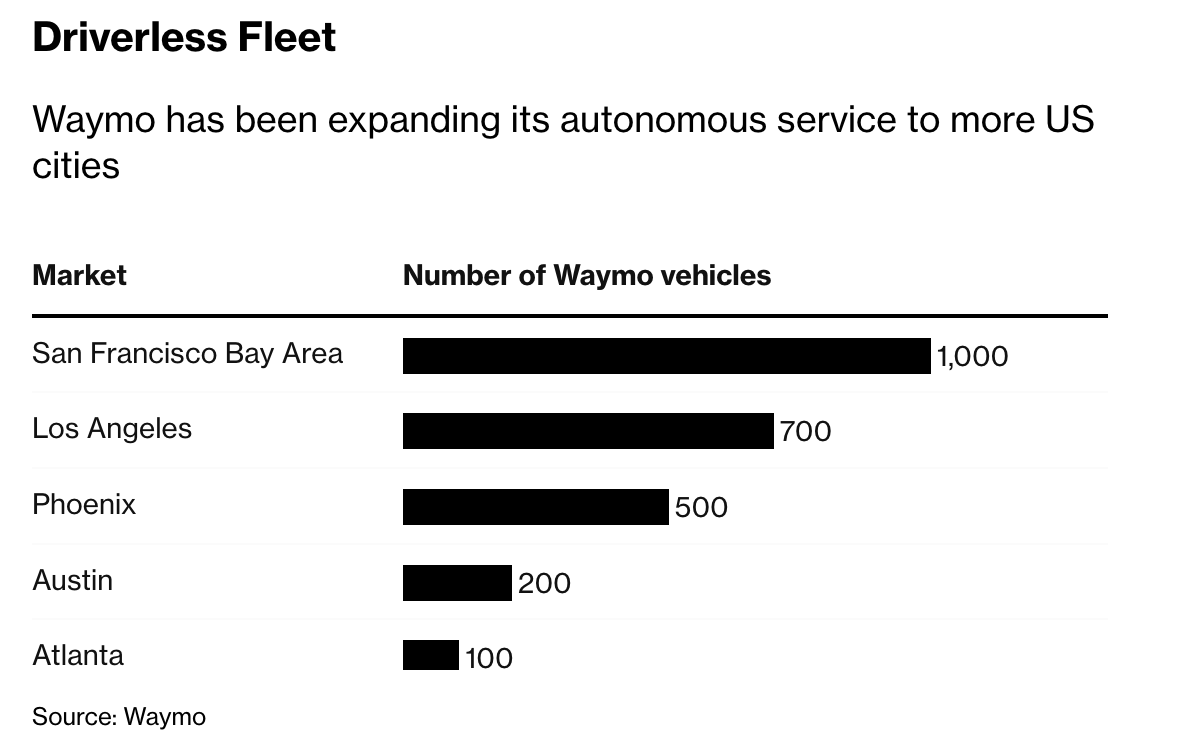
Source: Bloomberg
These numbers appear small given Waymo’s aggressive service area expansion. The company has launched five U.S. metros and announced plans to enter Dallas, Miami, Nashville, Las Vegas, Detroit, San Diego, and London next year. The service footprint is growing rapidly but the vehicle supply isn’t keeping pace.
This creates a fundamental mismatch: Waymo has solved the technology problem and unlocked a compelling product, but can it deliver at scale?
Freeway capability is meaningless if wait times stretch to 20 minutes because there aren’t enough cars to meet demand. And in the ride-hailing business, wait times are super important.
The OEM Partnership Bottleneck
Waymo’s manufacturing strategy relies on partnerships with original equipment manufacturers. The company announced a deal with Hyundai to integrate its autonomous technology into the IONIQ 5, and test vehicles have started appearing on San Francisco streets. But these are currently upfitted prototypes, not production-line vehicles. The hardware is being retrofitted after the car leaves the factory, an expensive, slow, and ultimately unscalable process.
Waymo’s previous partnership with Zeekr followed a similar trajectory. Test vehicles appeared months ago, but integration has taken far longer than anticipated. Industry observers expect it will be late 2026 before Hyundai-based robotaxis begin entering service in meaningful numbers, and even then, production will ramp slowly.
This timeline problem is existential. Waymo needs thousands of new vehicles annually to maintain its lead, but the OEM partnerships, at least as currently, can’t deliver that velocity. The company had a brief partnership announcement with Toyota, but nothing has materialized publicly. There are no signs of additional OEM deals on the horizon.
The Competitive Picture
Waymo holds the lead, but others are moving fast. Chinese robotaxi operator Baidu announced 17 million rides completed across 22 cities and already operates on highways in Abu Dhabi (with safety drivers). Uber’s partnership with Avride aims to deploy 500 Hyundai-based robotaxis in Dallas next year, potentially matching Waymo’s Phoenix fleet size in a single market launch. And there are many other companies like Nuro, Wayve, May Mobility and more.
Tesla remains the wildcard. The company’s Full Self-Driving software is improving, and IF it reaches true unsupervised capability, the manufacturing advantage becomes insurmountable.
The Path Forward
Waymo’s freeway unlock is a genuine achievement. It transforms the product from a local novelty into a regional utility, unlocks critical revenue streams like airport trips, and demonstrates the company’s ability to master the full spectrum of driving environments. The 260-square-mile Bay Area service area is genuinely impressive.
But none of that changes the central challenge: Waymo needs 10,000 vehicles in service, not 2,500. It needs a manufacturing engine that can produce hundreds of cars monthly, not dozens. And it needs that engine operational fast, before competitors close the technology gap and render Waymo’s head start irrelevant.
The freeway announcement is exciting because it shows what’s possible. But excitement isn’t the same as inevitability. Waymo has proven it can build the best autonomous vehicle technology in the world. Now it has to prove it can manufacture it at scale. That’s a different problem, requiring different skills, and the clock is ticking.
The next major Waymo announcement worth watching isn’t another city launch or another technical milestone. It’s a massive OEM deal with clear production timelines or evidence that the Hyundai and Zeekr partnerships are ramping faster than expected. Until we see that, the freeway unlock remains an impressive feature trapped inside an undersized fleet.
🔗 WIRED / Bloomberg / Forbes / TechCrunch / Road to Autonomy
Enjoying the AV Market Strategist?
If you find value in these deep-dives and enjoy the updates on autonomy each week — you can support my work.
Your contribution helps me access better data sources, industry reports, and research tools to keep every issue sharper and more insightful.
The newsletter will always remain free to read, whether you choose to support or not — but every bit of backing helps me make it even better.
🚛 Autonomous Trucking’s —SPACs, Scale, and the Path to Profitability
The autonomous trucking sector took another major step toward public market maturity this week as Swedish startup Einride announced plans to go public via SPAC merger, becoming the third autonomous trucking company to pursue this path in 2025. The announcement came just days before Kodiak AI—which completed its own SPAC merger in September—reported its first quarterly earnings as a public company, offering transparency into the operational and financial realities of commercializing driverless freight technology.
Einride’s $1.8 Billion SPAC: Europe Enters the Public Arena
Einride announced Wednesday it will merge with special purpose acquisition company Legato Merger Corp. III in a transaction valuing the Stockholm-based company at $1.8 billion in pre-money equity. The deal is expected to generate approximately $219 million in gross proceeds before accounting for potential redemptions of Legato’s public shares, transaction expenses, or additional financing. Einride is also seeking up to $100 million in private investment in public equity (PIPE) capital to accelerate growth.
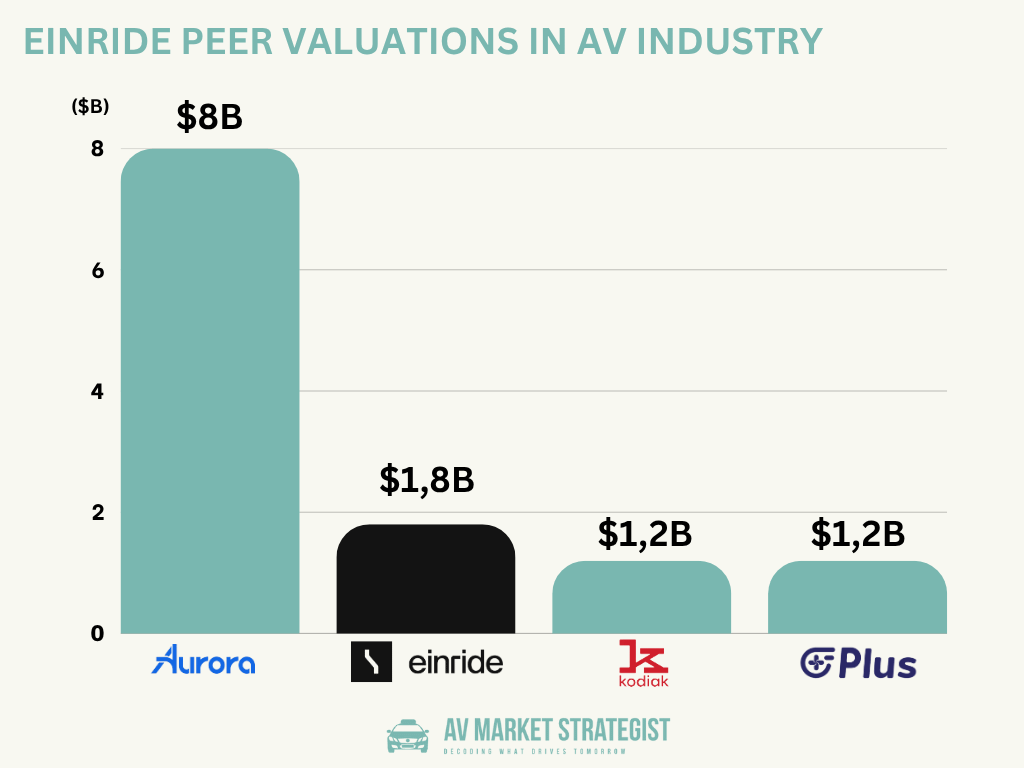
The merger is expected to close in the first half of 2026, culminating in a New York Stock Exchange listing. Upon closing, existing Einride shareholders will own approximately 83% of the pro-forma equity, assuming the company raises the full $100 million PIPE.
The timing is striking: Einride raised $100 million just six weeks ago in October from existing and new institutional investors including a West Coast-based global asset manager, EQT Ventures, and NordicNinja. That capital infusion, combined with the SPAC proceeds and potential PIPE financing, positions the company with substantial resources to execute its expansion plans across North America, Europe, and the Middle East.
Einride disclosed operational metrics:
Over 1,700 driverless hours in contracted customer operations
350,000+ shipments executed with a 99.7% on-time performance rate
~$45 million ARR run-rate with $65 million in total contracted ARR from signed customer contracts
$800+ million in potential long-term ARR within Joint Business Plans—detailed scaling agreements with customers for continued electric and autonomous deployment expansion
~200 electric vehicles currently managed across seven countries in North America, Europe, and the Middle East
25+ enterprise customers including PepsiCo, Heineken, Carlsberg, Mars, GE Appliances, and Apote
CEO Roozbeh Charli, who joined earlier this year, framed the SPAC route as offering “faster and more efficient” access to public markets. “We’ve proven the technology, built trust with global customers, and shown that autonomous and electric operations are not just possible, but better,” he said. “This transaction positions us to accelerate our global expansion and continue to deliver with speed and precision for our customers.”
A Different Business Model: Vertical Integration vs. Virtual Driver
Most autonomous trucking players like Aurora, Kodiak, and Plus are developing what can be described as a “virtual driver” strategy. They build autonomous driving software that can be licensed to fleet operators, logistics companies, or OEMs. The model is capital-light: develop sophisticated AI, partner with truck manufacturers for hardware integration, and license the technology across many vehicles without owning physical assets. Revenue comes from software licensing, per-mile fees, or driver-as-a-service contracts.
Einride is pursuing full vertical integration across the entire electrified autonomous freight stack. The company operates through a dual revenue model:
Freight-Capacity-as-a-Service (FCaaS): Einride provides end-to-end freight services using both driver-operated heavy-duty electric trucks and heavy-duty autonomous electric trucks. This isn’t just software licensing, it’s owning and operating the trucks, managing charging infrastructure, optimizing battery systems, and handling full operational logistics under take-or-pay contracts averaging 4.5 years with minimum volume commitments.
Software-as-a-Service (SaaS): Einride licenses its proprietary technology platform to third parties, including operational planning AI software and the company’s autonomous driving system. Critically, the technology stack is vessel-agnostic, meaning it can be deployed across multiple vehicle platforms beyond Einride’s own cab-less trucks, opening revenue streams in defense and specialized civilian applications.
This vertical integration strategy offers control and the ability to capture value at multiple layers of the stack, but it also multiplies capital requirements, operational complexity, and points of failure. The company must excel at software development, hardware integration, fleet operations, charging infrastructure management, customer relationships, and regulatory compliance simultaneously.
Geographic and Regulatory Arbitrage
Einride’s positioning is particularly interesting through a geopolitical lens. The company operates across three distinct regulatory and market environments. Europe, North America, and the UAE, each moving at different speeds on electrification and autonomy.
In Europe, electrification mandates are driving demand for electric trucks, but autonomous vehicle regulation remains fragmented and moves slowly. In the United States, the electrification cycle is cooling as political winds shift, but autonomy regulation is accelerating, particularly for trucking applications where labor shortages create economic urgency. The UAE represents a third path: aggressive government support for both technologies as part of broader smart-city ambitions.
Einride sits at the intersection of all three cycles, which creates optionality but also complexity. The company must navigate different regulatory frameworks, infrastructure requirements, and customer expectations simultaneously. This geographic diversification reduces concentration risk but increases execution difficulty, particularly for a company that’s still pre-profitability and burning cash to build out physical infrastructure.
The 2025 SPAC Wave: Autonomous Trucking Embraces Public Markets
Einride is the third autonomous trucking company to announce a SPAC merger in 2025, reflecting a broader industry trend toward public market access.
Kodiak AI completed its SPAC merger with Ares Acquisition Corporation II in September and began trading on Nasdaq. Plus AI announced its SPAC merger and expects to close the transaction in early 2026. Even Aurora went public via SPAC merger in 2021.
The SPAC wave reflects both opportunity and necessity. On one hand, these companies have real technology, paying customers, and credible paths to profitability within 3-5 years. That’s vastly different from the speculative SPAC deals that collapsed post-2021 when the market sobered up and demanded actual business fundamentals. On the other hand, the SPAC route often signals difficulty raising additional private capital at attractive valuations.
Public markets offer permanent capital and liquidity for early investors, but they impose quarterly reporting requirements, earnings pressure, and stock price volatility that can distract management from long-term execution. The tradeoff is whether transparency and market discipline accelerate progress or create short-term pressures that undermine patient capital allocation.
Kodiak’s Q3 Earnings
One of these newly public autonomous trucking companies reported earnings this week. Kodiak AI announced third-quarter results Tuesday, marking the company’s first earnings report since completing its SPAC merger.
Operational Highlights:
10 fully driverless trucks deployed with Atlas Energy Solutions in the Permian Basin (100% increase from Q2)
5,200+ cumulative hours of paid driverless operations through Q3 (166% increase from Q2)
3 million autonomous miles driven and over 10,000 loads delivered for customers
Manufacturing partnership with Roush Industries completed production of first driverless-ready truck, enhancing scalability
These metrics demonstrate genuine commercial momentum. Kodiak is operating truly driverless trucks—no safety driver, no remote operator—generating revenue from paying customers in a real industrial environment.
The Permian Basin operations with Atlas Energy Solutions prove the business model works in controlled environments with predictable routes and financially motivated customers.
Looking at long-haul trucking, Kodiak anticipates launching long-haul driverless operations in the second half of 2026.
Why Public Companies Are Good for Autonomous Trucking
The emergence of multiple public autonomous trucking companies—Kodiak now trading, Plus and Einride expected to list in 2026, Aurora already public since 2021—is genuinely positive for the industry.
Public reporting creates transparency that benefits the entire ecosystem by establishing clear benchmarks for progress. This comparability attracts capital, improves execution discipline through quarterly analyst scrutiny, provides liquidity for early believers, and signals market validation to regulators and customers.
The next 12 months will be exceptionally clarifying. Kodiak must launch long-haul operations on schedule in H2 2026. Einride must close its SPAC and prove vertical integration generates superior returns. Plus must complete its transaction and show progress. All of this plays out transparently through quarterly earnings, analyst scrutiny, and stock performance. Looking forward to see all this unfold!
🔗 TechCrunch / Bloomberg / Kodiak AI (1) / Kodiak AI (2) / Forbes
💡 Quick Takes
WeRide receives UAE’s first fully driverless commercial Robotaxi license
WeRide secured approval from the UAE federal government to operate fully driverless Level 4 Robotaxis in Abu Dhabi—the first city-level commercial license for autonomous driving outside the United States. Issued by the UAE Cabinet Secretariat’s Regulations Lab, the authorization allows WeRide to remove safety operators from vehicles serving customers through Uber and TXAI platforms.
🔗 Gasgoo
Baidu’s Apollo Go and AutoGo secure Abu Dhabi’s inaugural fully driverless commercial permit
Baidu’s Apollo Go robotaxi service and UAE-based AutoGo received one of Abu Dhabi’s first fully driverless commercial permits from the Integrated Transport Centre, authorizing public robotaxi operations without safety drivers. The partnership, announced in March 2025, progressed from initial testing to fully driverless operations in just months. The companies plan large-scale deployment of hundreds of autonomous vehicles by 2026, with the goal of building Abu Dhabi’s largest fully driverless fleet.
Vietnam and China test cross-border autonomous freight trucks
Vietnam and China jointly conducted the first night-time trial of driverless electric container trucks transporting goods across their shared border. The trucks, equipped with cameras and sensors, followed pre-programmed routes from China into Vietnam at the Tan Thanh-Puzhai crossing. Drivers remained on board during the test to monitor systems. The pilot is part of a $304 million smart border gate initiative aimed at increasing daily cargo throughput to 2,500-3,000 trucks and reducing customs clearance costs by 30-40%.
HOLON receives nationwide autonomous testing approval
HOLON secured approval from Germany’s Federal Motor Transport Authority (KBA) to test its Level 4 autonomous shuttle throughout the country with a safety driver. The HOLON urban vehicle will begin real-world testing in Hamburg as part of the ALIKE project, covering 37 square kilometers of urban roads. The approval, valid through 2026 with extension options, excludes motorways but allows testing on federal, state, and district roads.
🔗 Benteler
South Korea targets 2028 for autonomous vehicle mass production
South Korea’s government unveiled an aggressive plan to mass-produce autonomous vehicles by 2028, backed by 15 trillion won ($11.4 billion) in policy financing for the domestic auto industry. The strategy includes developing AI-powered “end-to-end” autonomous driving systems, establishing a 500 billion won Future Vehicle Industry Technology Innovation Fund, and training 70,000 professionals in AI and autonomous driving.
Grab invests $60M in German remote-driving startup Vay, with $350M more pending milestones
Singaporean super-app Grab will inject $60 million into Vay, a Berlin-based startup offering remotely-operated rental cars, with up to $350 million in additional funding contingent on hitting U.S. expansion milestones. Vay’s service, where remote operators drive cars to customers who then take over, is currently operational in Las Vegas and costs about half the price of ride-hailing. The deal signals Grab’s growing mobility ambitions following investments in May Mobility and WeRide.
Military AV startup Forterra hits $1B+ valuation
Forterra raised $238 million ($50M debt, $188M equity) in a round led by Moore Strategic Ventures, pushing its valuation above $1 billion. The Maryland-based company produces autonomous systems for military vehicles capable of operating individually or in swarms, with hundreds currently deployed, including some conducting mine-sweeping in active combat zones. Forterra will use the funds to double production to 1,000 systems in 2026 and expand mission scope to include missile launches and mobile AI infrastructure.
📚 Worth Reading/Listening
Goldman Sachs Talks At GS: Dara Khosrowshahi, CEO of Uber
Timothy B. Lee, Understanding AI: Waymo is finally ready for freeway service
🔗 Understanding AI
📊 Weekly Performance
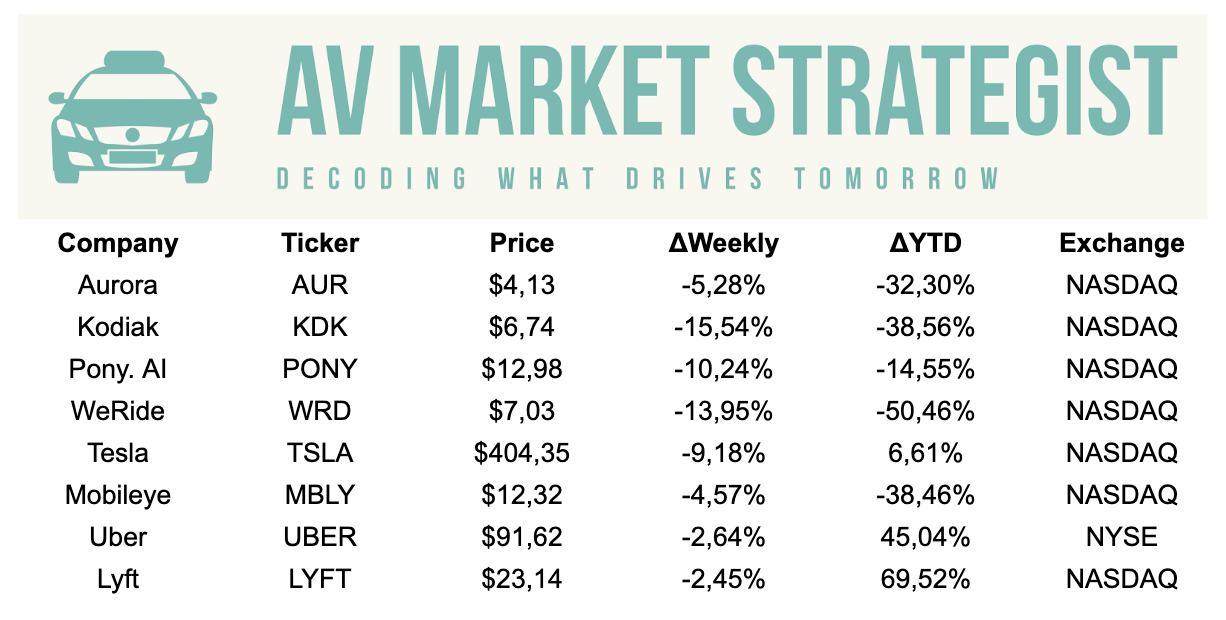
Note: Stock performance data as of November 16, 2025. Past performance does not indicate future returns.
Thanks for reading!
If you found value in this newsletter, please consider sharing it with a friend or colleague who might benefit from these insights.
And if you haven’t already, subscribe to stay updated on the latest developments in the autonomous driving industry.
Disclaimer: This newsletter is for informational purposes only and should not be considered investment advice. All opinions are my own.
Love this perpective. What if scaling past freeways introduces unseen algorithmic complexity?